

Asian Diary - May 2015
Asia ex Japan Equities fell 2.6% over May1, outperforming broader emerging markets which were down 4%2, but underperforming many developed markets. Having been the weakest markets in the region in April, India (2.8%) and Indonesia (2.8%) were the only markets to generate a positive return in May, possibly helped by weaker US economic data viewed as potentially delaying the start of US rate increases. Malaysia was the weakest market (-6.4%) due to ongoing political noise and poor earnings. Meanwhile, China declined -3.7% in the offshore market despite onshore A-shares rising 4.9%. China remains the focus of news flow in the region as investors seek to reconcile weaker economic data with government efforts to stabilise growth and stimulate the stock market. Another 25bp rate cut from the People’s Bank of China in May failed to excite investors.
During the month our energy analyst was in Taiwan and South Korea to meet a number of chemicals companies. The purpose of the trip was to conduct further due diligence of a stock in the space we rate highly by meeting some of its peers. Evidence collected from the trip suggested that chemicals companies in the region will continue to see margins expand in the near term due to the lower oil price, which should be good for the stock we are tracking. But given the high cyclicality of these businesses we should be cautious about the outlook as we move later into the year.
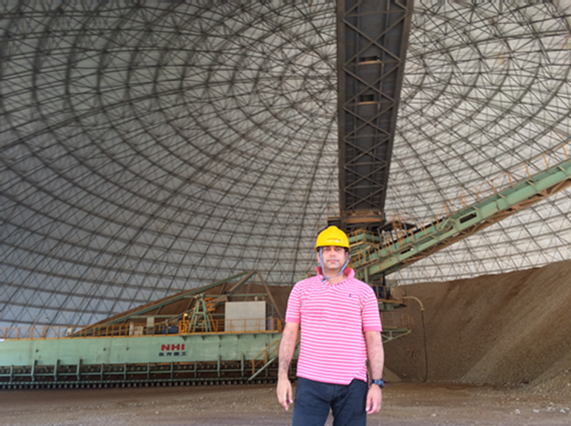
The same analyst was also in Indonesia last month meeting cement companies, industry consultants, distributors, and the local industry trade body. He came away concerned about over supply in the market over the next few years, especially as demand has recently been declining. The trade body told him that total capacity in the industry would increase by 50% over the coming 3 years. We would need to see a dramatic pick up in housing and infrastructure demand to take up that slack. More positively, he visited the local operations of one of his buy-rated Chinese cement stocks. The company is expanding capacity in Kalimantan, one of Indonesia’s largest but less developed islands. The company hopes to dominate the local market on that island. He was impressed with the efficiency of their operations which gives him confidence that their plans to expand into other parts of Asia (Myanmar, ASEAN) may also be well executed. Here he is on location in the limestone storage area of the Kalimantan plant.
Elsewhere, Portfolio Manager Eric Moffett, joined one of our Baltimore based analysts at the YUM! Brands analyst days in China and India. China represents 40% of YUM’s EBIT, largely through KFC, and has been the key stock price driver in recent years. India on the other hand is currently loss making, but the company is excited by the longer term opportunity there. In recent years KFC has been hit by food quality scandals, and by rapidly increasing competition in the casual restaurant sector. The trip helped the team understand the recovery that is taking place in YUM! China, whilst also highlighting that the high growth phase the company saw in the mid-2000s has faded and is unlikely to return.
Eric also took the opportunity to visit a range of other consumer and industrial companies in China. To prove that business travel is not especially glamorous, his due diligence included stays at a budget hotel chain rated by our team. He paid just $30-50/night for hotels in central Shanghai and was generally impressed by the locations, the cleanliness and the staff, but found a couple of things broken in each of his rooms – which gives us something to follow up on next time we meet with company management.
重要情報
当資料は、ティー・ロウ・プライス・アソシエイツ・インクおよびその関係会社が情報提供等の目的で作成したものを、ティー・ロウ・プライス・ジャパン株式会社が翻訳したものであり、特定の運用商品を勧誘するものではありません。また、金融商品取引法に基づく開示書類ではありません。当資料における見解等は資料作成時点のものであり、将来事前の連絡なしに変更されることがあります。当資料はティー・ロウ・プライスの書面による同意のない限り他に転載することはできません。
資料内に記載されている個別銘柄につき、売買を推奨するものでも、将来の価格の上昇または下落を示唆するものでもありません。また、当社ファンド等における保有・非保有および将来の組入れまたは売却を示唆・保証するものでもありません。投資一任契約は、値動きのある有価証券等(外貨建て資産には為替変動リスクもあります)を投資対象としているため、お客様の資産が当初の投資元本を割り込み損失が生じることがあります。
当社の運用戦略では時価資産残高に対し、一定の金額までを区切りとして最高1.265%(消費税10%込み)の逓減的報酬料率を適用いたします。また、運用報酬の他に、組入有価証券の売買委託手数料等の費用も発生しますが、運用内容等によって変動しますので、事前に上限額または合計額を表示できません。詳しくは契約締結前交付書面をご覧ください。
「T. ROWE PRICE, INVEST WITH CONFIDENCE」および大角羊のデザインは、ティー・ロウ・プライス・グループ、インクの商標または登録商標です。
ティー・ロウ・プライス・ジャパン株式会社
金融商品取引業者関東財務局長(金商)第3043号
加入協会:一般社団法人日本投資顧問業協会/一般社団法人投資信託協会

