

European High Yield
Just how defensive are BB rated European high yield bonds in today's markets?
Since the launch of our European High Yield Bond portfolio back in 2011, I have always had a bias for looking beyond the BB-rated universe. The research our high yield analysts carry out to identify long-term positive stories–where the income profile is attractive and the potential for capital gains most rewarding for our clients–has found that the best opportunities often lie in the single-B rated space.Holding a structural underweight in BB-rated companies however, I often get asked whether the risk profile of our European High Yield approach is potentially higher than that of the markets. This was certainly the case during the so called “taper tantrum” episode of 2013, when BB-rated names held up much better than B and CCC-rated securities.
The second quarter of 2015 has depicted a different picture though, despite a similar environment of heightened volatility and fears of higher interest rates (see chart below). Contrary to expectations, B-rated names have resisted well in the sell-off environment (down 0.74% in euro terms*) while BB-rated securities have strongly underperformed the rest of the high yield universe, generating an absolute return of -1.43%* for the quarter.
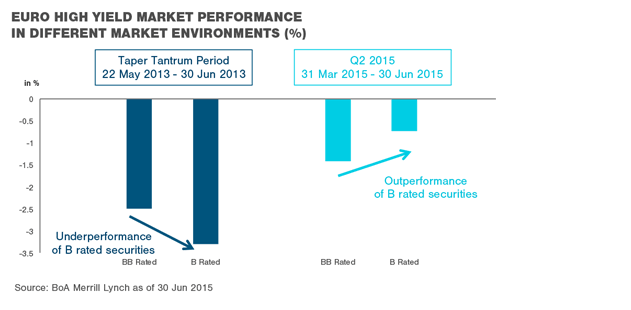
Why? A clue may lie in looking at the spread correlation that currently exists between the European investment grade market and the BB-rated high yield sector. BB-rated securities have been strongly impacted in the last quarter by the negative performance of the investment grade corporate bond sector. This impact may well be a sign that the current market volatility is spooking a number of investment grade managers, who have in the past owned BB-rated names as simple cross-over holdings and are now reducing risk in their portfolios by selling those lower rated securities.
The second reason may well be related to portfolio management and liquidity raising at times of outflows. Keeping in mind that BB-rated securities make up a much higher proportion of the EHY market (>60%)*, they are more likely to be sold to raise liquidity when needed.
Taking this all into account really does bring into question just how defensive BB-rated securities are during periods of volatility. I remain convinced that B-rated companies offer the best investment possible for European high yield investors, particularly since holding them does not automatically raise the risk profile of our portfolio relative to the market.
* Source: BoA Merrill Lynch, as at 30 Jun 2015
2015-GL-2158
重要情報
当資料は、ティー・ロウ・プライス・アソシエイツ・インクおよびその関係会社が情報提供等の目的で作成したものを、ティー・ロウ・プライス・ジャパン株式会社が翻訳したものであり、特定の運用商品を勧誘するものではありません。また、金融商品取引法に基づく開示書類ではありません。当資料における見解等は資料作成時点のものであり、将来事前の連絡なしに変更されることがあります。当資料はティー・ロウ・プライスの書面による同意のない限り他に転載することはできません。
資料内に記載されている個別銘柄につき、売買を推奨するものでも、将来の価格の上昇または下落を示唆するものでもありません。また、当社ファンド等における保有・非保有および将来の組入れまたは売却を示唆・保証するものでもありません。投資一任契約は、値動きのある有価証券等(外貨建て資産には為替変動リスクもあります)を投資対象としているため、お客様の資産が当初の投資元本を割り込み損失が生じることがあります。
当社の運用戦略では時価資産残高に対し、一定の金額までを区切りとして最高1.265%(消費税10%込み)の逓減的報酬料率を適用いたします。また、運用報酬の他に、組入有価証券の売買委託手数料等の費用も発生しますが、運用内容等によって変動しますので、事前に上限額または合計額を表示できません。詳しくは契約締結前交付書面をご覧ください。
「T. ROWE PRICE, INVEST WITH CONFIDENCE」および大角羊のデザインは、ティー・ロウ・プライス・グループ、インクの商標または登録商標です。
ティー・ロウ・プライス・ジャパン株式会社
金融商品取引業者関東財務局長(金商)第3043号
加入協会:一般社団法人日本投資顧問業協会/一般社団法人投資信託協会
