The new economics of building things | 2027 Global Market Outlook
November 2026, Equity
For much of the post‑global financial crisis period, abundant capital and low interest rates favored asset‑light businesses with high margins and strong free cash flow. Today, a different set of forces is reshaping the investment landscape—one in which rising capex is making physical capacity, infrastructure, and specialized equipment increasingly valuable.
COVID exposed vulnerabilities in global supply chains. Geopolitical tensions have increased the emphasis on energy security, defense, electrification, and domestic production. At the same time, the AI infrastructure build‑out is creating enormous demand for power, data centers, semiconductors, and other physical assets.
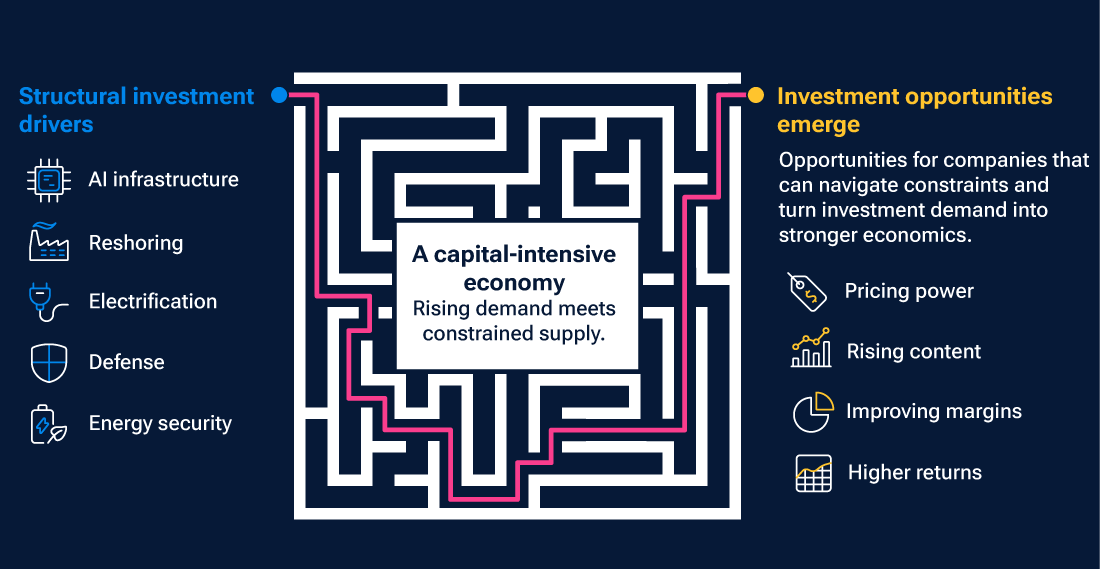
Together, these forces are driving a more capital‑intensive investment cycle that we believe could run for five to 10 years (Figure 1). Cycles like this are slow to build and slow to fade. Expanding physical capacity takes time, particularly where infrastructure, skilled labor, and specialized equipment are in short supply. This could create a prolonged period of strong demand and improving returns for companies positioned to overcome these constraints.
From capex boom to investment winners
(Fig. 1) Multiple forces are driving a new investment cycle
Source: T. Rowe Price.
A broader investment universe
The change is already visible across a wider range of businesses. Companies with pricing power are turning higher nominal growth into stronger revenues and margins. Those with high fixed costs can benefit as stronger revenues translate into greater operating leverage. And some businesses previously dismissed as too cyclical, capital intensive, or structurally challenged are seeing stronger demand, better pricing, and improving profitability.
Industrials are part of that story, but not the whole story. The opportunity set extends across financials, energy, materials, semiconductors, and infrastructure. For investors, the challenge is to recognize when changing conditions are improving a company’s economics—and whether those improvements are reflected in its valuation.
Find improving economics
For investors, the useful question is not “Which sectors are benefiting?” but “Which companies are becoming better businesses?” Scarce capacity, for example, can give a company’s products or services far greater value.
In industrials, higher investment may create opportunities for businesses that enable customers to become more productive. In financials, banks and insurers may benefit from higher interest rates through improved lending margins and investment income, although the impact will depend on funding costs, credit quality, and the shape of the yield curve.
That distinction matters because powerful themes do not automatically produce attractive investments. Capital eventually responds to high returns. Supply can increase, bottlenecks can ease, and pricing power can fade. China adds another dimension to this investment cycle. Its enormous manufacturing capacity and ability to mobilize capital can accelerate the deployment of new technologies but also create supply responses that commoditize parts of the value chain and erode returns. As the U.S. and China compete for leadership in critical technologies such as AI, investors must distinguish businesses with durable competitive advantages from those vulnerable to new sources of competition.
Rebuilding investment muscles
A changing regime requires investors to challenge assumptions formed in the previous one. Rebuilding investment muscles means applying familiar disciplines to a changing investment landscape.
Investors must assess whether improving demand will last, whether companies can defend their returns as competition increases, and whether valuations already reflect these prospects. The opportunity lies in identifying businesses whose economics are improving more durably—and faster—than the market expects.
Key takeaway
As the physical economy rebuild gathers pace, investors should look beyond traditional growth sectors to identify businesses where improving demand is driving stronger margins and returns on capital—and where the market has yet to recognize the change.
Market value of holdings shown are illustrative and may differ from the values used to calculate the fund’s net asset value (“NAV”). For information on valuation of portfolio assets used to calculate NAV, please see the prospectus.
ETFs/ETPs are bought and sold at market prices, not NAV. Investors generally incur the cost of the spread between the prices at which shares are bought and sold. Buying and selling shares may result in brokerage commissions which will reduce returns.
202611- 6051971
 Jason Adams
Portfolio Manager
 Nabil Hanano, CFA
Associate Portfolio Manager
Strategies to Consider
- Nov 2026
Bonds are paying their way again | 2027 Global Market Outlook

- Nov 2026
2027 Global Market Outlook

Contact us
Appendix
T. Rowe Price cautions that economic estimates and forward-looking statements are subject to numerous assumptions, risks, and uncertainties, which change over time. Actual outcomes could differ materially from those anticipated in estimates and forward-looking statements, and future results could differ materially from any historical performance. The information presented herein is shown for illustrative, informational purposes only. Any historical data used as a basis for this analysis are based on information gathered by T. Rowe Price and from third-party sources and have not been independently verified. Forward-looking statements speak only as of the date they are made, and T. Rowe Price assumes no duty to and does not undertake to update forward-looking statements.
Financial terms: Investors in the U.S. and Canada, for a glossary of financial terms, please go to troweprice.com/glossary.
Investment risks:
Active investing may have higher costs than passive investing and may underperform the broad market or passive peers with similar objectives. Each person’s investing situation and circumstances differ. Investors should take all considerations into account before investing.
International investments can be riskier than U.S. investments due to the adverse effects of currency exchange rates, differences in market structure and liquidity, as well as specific country, regional, and economic developments. The risks of international investing are heightened for investments in emerging market and frontier market countries. Emerging and frontier market countries tend to have economic structures that are less diverse and mature, and political systems that are less stable, than those of developed market countries.
Commodities are subject to increased risks such as higher price volatility and geopolitical and other risks. Commodity prices can be subject to extreme volatility and significant price swings.
Inflation‑linked bonds (Treasury inflation protected securities in the U.S.): In periods of no or low inflation, other types of bonds, such as U.S. Treasury bonds, may perform better than Treasury inflation protected securities (TIPS).
Investing in technology stocks entails specific risks, including the potential for wide variations in performance and usually wide price swings, up and down. Technology companies can be affected by, among other things, intense competition, government regulation, earnings disappointments, dependency on patent protection, and rapid obsolescence of products and services due to technological innovations or changing consumer preferences.
Because of the cyclical nature of natural resource companies, their stock prices and rates of earnings growth may follow an irregular path.
Financial services companies may be hurt when interest rates rise sharply and may be vulnerable to rapidly rising inflation. Health sciences firms are often dependent on government funding and regulation and are vulnerable to product liability lawsuits and competition from low‑cost generic products.
The value approach to investing carries the risk that the market will not recognize a security’s intrinsic value for a long time or that a stock judged to be undervalued may actually be appropriately priced. Growth stocks are subject to the volatility inherent in common stock investing, and their share price may fluctuate more than that of income‑oriented stocks.
Small‑cap stocks have generally been more volatile in price than the large‑cap stocks. Investing in private companies involves greater risk than investing in stocks of established publicly traded companies. Risks include potential loss of capital, illiquidity, less available information, and difficulty in valuating private companies. They are not suitable, nor available, for all investors.
All investments involve risk, including possible loss of principal. Diversification cannot assure a profit or protect against loss in a declining market. Index performance is for illustrative purposes only and is not indicative of any specific investment. Investors cannot invest directly in an index.
Fixed income securities are subject to credit risk, liquidity risk, call risk, and interest rate risk. As interest rates rise, bond prices generally fall. Investments in high yield bonds involve greater risk of price volatility, illiquidity, and default than higher‑rated debt securities. Investments in bank loans may at times become difficult to value and highly illiquid; they are subject to credit risk, such as nonpayment of principal or interest, and risks of bankruptcy and insolvency. Some or all alternative investments, such as private credit, may not be suitable for certain investors.
Investments in private markets are speculative and involve a substantial degree of risk, including the possible loss of all or a substantial portion of an investment. Private market investments may be illiquid, difficult to value and subject to restrictions on transfer, and there may be no readily available secondary market. They may also employ leverage or other investment techniques that can increase the risk of loss. Fees and expenses associated with private market investments may be higher than those of traditional investments and will reduce investment returns. Private market investments may not be suitable for all investors and generally require a long‑term investment horizon and the ability to tolerate limited liquidity and substantial fluctuations in value. Investors should carefully consider their investment objectives, financial circumstances, risk tolerance and the specific risks of an investment before investing.
Important Information
This material is being furnished for informational and/or marketing purposes only and does not constitute an offer, recommendation, advice, or solicitation to sell or buy any security.
Prospective investors should seek independent legal, financial and tax advice before making any investment decision. T. Rowe Price group of companies including T. Rowe Price Associates, Inc. and/or its affiliates receive revenue from T. Rowe Price investment products and services.
Past performance is not a guarantee or a reliable indicator of future results. All investments involve risk, including possible loss of principal.
Information presented has been obtained from sources believed to be reliable, however, we cannot guarantee the accuracy or completeness. The views contained herein are those of the author(s), are as of November 2026, are subject to change, and may differ from the views of other T. Rowe Price Group companies and/or associates. Under no circumstances should the material, in whole or in part, be copied or redistributed without consent from T. Rowe Price.
All charts and tables are shown for illustrative purposes only. Actual future outcomes may differ materially from any estimates or forward‑looking statements provided.
The material is not intended for use by persons in jurisdictions which prohibit or restrict the distribution of the material and in certain countries the material is provided upon specific request.
Issued in the USA by T. Rowe Price Investment Services, Inc., distributor and T. Rowe Price Associates, Inc., investment adviser, 1307 Point Street, Baltimore, MD 21231, which are regulated by the Financial Industry Regulatory Authority and the U.S. Securities and Exchange Commission, respectively.
© 2026 T. Rowe Price. All Rights Reserved. T. Rowe Price, INVEST WITH CONFIDENCE, the Bighorn Sheep design, and related indicators (see troweprice.com/ip) are trademarks of T. Rowe Price Group, Inc. All other trademarks are the property of their respective owners. Use does not imply endorsement, sponsorship, or affiliation of T. Rowe Price with any of the trademark owners.
- 202610‑6005119