

Global Fixed Income: Time to Rethink Volatility Risk in Bond Portfolios
Executive Summary
- Volatility returned to markets with a vengeance during the summer amid growing concerns about China, sharp declines in commodity prices, and uncertainty over whether the U.S. Federal Reserve would raise rates in September.
- In such an environment, investors may benefit from looking beyond the benchmark and considering the full range of the fixed income universe, in particular, regions and countries that are less correlated to major markets such as the U.S. and China.
- To be truly “benchmark agnostic,” it is also important to be able to capture returns in both rising and falling markets through long and short positions.
- A portfolio that is not constrained by a benchmark, but still contains the best investment ideas, should fulfill fixed income’s role as a diversifier and a provider of sustainable income and capital preservation.
What a difference a few weeks can make. At the beginning of August global equity markets were calm to the point of being complacent. By the end of the month, many were in full-blown panic mode—and they have not calmed down much since. The dramatic shift in mood was prompted by a number of factors, including the slowing Chinese economy, the slump in commodity prices, and continued speculation about whether or not the Fed would raise interest rates in September. The upshot? The global investment landscape has become a more volatile and uncertain place than it was a few months ago—and the need for flexibility in bond portfolios is greater than ever.
CONCERNS ABOUT CHINA FUEL TURMOIL
China has been the epicenter as it struggles with its attempt to transition from the investment- and export-led boom of recent times to a more sustainable demand-led model. Amid growing uncertainty over China’s true growth rate, the Shanghai Composite Index declined by more than 40% off its peak from mid-June to the end of September. The clumsy way in which the Chinese authorities managed the devaluation of the renminbi, and their desperate and ultimately unsuccessful bid to prop up the stock market, have prompted growing suspicions that the government’s traditional control over its economy is waning.
But it hasn’t just been about China. Concerns about global growth have led to commodity prices falling, which has also contributed to higher volatility. When oil prices first fell in the second half of last year, many expected the price drop to lead to a fall in production, keeping the market in balance. Instead, many producers maintained production levels, keeping supply high despite lower prices. This has created something of a feedback loop through which the commodity sell-off can be seen as both a cause and a consequence of the broader emerging markets panic: The slowdown in China and other emerging markets has lowered demand. High supplies and weak demand equals lower prices—which feeds back into weaker economic conditions for energy-producing countries like those in the Middle East, Latin America, and Russia.
Meanwhile, the looming prospect of the first Fed rate hike since 2006 has been putting further strain on investors’ already frayed nerves. The Fed’s announcement in September that it was keeping rates on hold, and the dovish language of the Federal Open Market Committee statement that accompanied it, did little to calm those nerves. Instead, speculation immediately began to build about whether the hike would come in late 2015, early 2016, or even further beyond that, with no clear consensus emerging. The result: further uncertainty, with no clear end in sight.
A DIFFERENT APPROACH TO BOND INVESTING
When volatility is high and the global macroeconomic picture is mixed, bond investors need to review their existing fixed income allocation to assess whether it provides them with enough freedom and flexibility to profit from relevant opportunities wherever they arise. This means considering the full spectrum of the fixed income universe, in particular regions and countries that are less correlated to major markets such as the U.S. and China.
The good news is that fixed income investors today have more choice than ever before. In countries where interest rates are rising, for example, steepening yield curves can offer income opportunities, while rising volatility on foreign exchange markets can lead to currency opportunities. Emerging markets can offer the higher yields that investors look for but may come with added risk, while lower-yielding, less risky securities still offer benefits in a period of highly volatile equity markets.
The bad news is that greater choice does not necessarily make the job of fixed income investors any easier— with more options comes the need for more research, due diligence, and risk management. However, investors who actively embrace this wider opportunity set are ultimately likely to find their efforts rewarded, while those who do not seek access to different country bond markets could miss potential performance enhancement and diversification.
And the opportunity set continues to expand and evolve. Since the 2008 financial crisis, more companies in Europe are accessing the public debt markets for their financing needs, which is fueling the growth of the euro high yield asset class. Similar trends are occurring among companies in the emerging markets—indeed, the EM corporate debt market is the fastest-growing fixed income asset class.
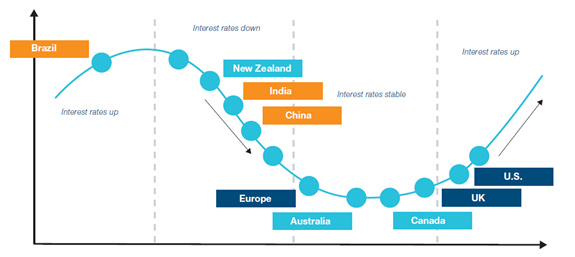
Investors with access to a broad range of markets can derive returns by taking positions in countries at differing stages of the interest rate cycle. Figure 1 illustrates a hypothetical interest rate cycle between a selected number of developed and emerging markets. It shows how an investor can take advantage of relative country exposures in markets where interest rates are falling or stable versus countries where interest rates are rising. This enables investors to not only exploit interest rate differentials between countries, but also adjust duration (price sensitivity to changes in interest rates) and yield curve exposures within individual countries. If yields are attractive but currency valuations are not, currency risk can be neutralized to focus exclusively on country selection.
FIGURE 1: Illustrative interest rate cycle
DEALING WITH DURATION
The latter point is worth exploring further. As some central banks begin raising rates, managing duration risk is going to become increasingly important—and there are different ways to achieve this. One approach is to buy securities at the front end of the curve, where interest rate sensitivity is low. With short rates in many developed markets still around zero, this would clearly mean sacrificing yield, although some short-dated high-quality corporate debt can provide modest yield over comparable sovereign debt with only marginally more risk.
Another approach is to consider floating rate notes such as bank loans, which feature virtually no duration as their coupons are adjusted in line with interest rates. Floating rates typically perform well in a rising rate environment, particularly if those rises are fueled by strong economic growth. However, as quality is sacrificed in the pursuit of yield, credit and liquidity risk can replace duration risk.
It is important to stress that tightening cycles should not necessarily be regarded negatively. By considering the level of tightening that the yield curve has already discounted, it is possible to find valuation opportunities at different maturity points. Local rates are driven primarily by domestic economic conditions and policy responses, and when different countries are at different points in their rate cycles, investors can take advantage of this with targeted duration exposures.
Some developing countries, for example Brazil and South Africa, have been raising rates for a while to combat high inflation and depreciating currencies. This led to money flowing into these economies as rates in advanced economies remained at rock bottom, but the prospect of a U.S. rate hike saw those funds flow back out as investors moved their money in the expectation of improved returns. Many other countries continue to experience muted inflation and are adopting softer monetary policies, while some Eastern European countries, for example Romania and Hungary, have very low inflation rates but offer higher yields than in the eurozone’s periphery. Meanwhile, some local markets typically exhibit lower volatility than global rates. Stable markets such as these should fare relatively well even when rates are rising elsewhere.
THE IMPORTANCE OF BEING AGNOSTIC
Retaining the ability to invest in different regions and countries can go a long way toward managing duration, particularly in a period of historically low rates and unconventional monetary policy. To be genuinely “benchmark agnostic,” however, it is also important to be able to capture returns in both rising and falling markets through long and short positions. During the 30-year bond bull market, investors in traditional long-only fixed income strategies linked to benchmarks such as the Barclays Global Aggregate Index enjoyed strong positive returns as yields fell and prices rose. However, as yields begin to rise again and prices fall, the ability to short certain markets and sectors and capture returns from falling prices will be extremely valuable.
By adopting a genuinely unconstrained bond strategy, an investor can seek value anywhere in the world irrespective of whether markets are going up or down. But this is not an easy strategy to adopt: the heterogeneous nature of the global bond universe means that the choices facing an unconstrained investor are seemingly endless. Success requires conviction—only those positions backed up with a high degree of confidence should be adopted.
This requires an in-depth analysis of the main macroeconomic indicators, such as economic growth, monetary policy developments, and inflation expectations, and an understanding of the impact these factors have on interest rates in the long term. Armed with this knowledge, investors can compare their expectations with the market consensus and identify where the best opportunities lie, both on the long and the short side.
RISING RATES, FALLING PRICES
The long period of accommodative monetary policy and subsequent search for yield that followed the financial crisis inflated bond prices to elevated levels across sovereign and credit markets. As central banks held down rates, bond investors benefited from low volatility and price appreciation. But as the U.S. Federal Reserve prepares to begin its hiking cycle, investors need to be prepared for a more volatile ride.
When rates rise, investors need protection against falling bond prices. This requires building a robust portfolio that is selective in country, currency, and credit exposures, and targets risk in areas that offer the most attractive value propositions while maintaining a range of defensive positions to protect against the downside.
Historically, “safe haven” currencies, such as the U.S. dollar and the Japanese yen, have risen in value during periods of investor fear. Maintaining some exposure to these reserve currencies can potentially limit losses from higher risk positions if investor sentiment turns negative.
On the other hand, risk-aware investors should underweight certain “carry” currencies that attract speculators who borrow low-yielding currencies to capture the yield differential. Crowded carry trades can quickly unwind when there are signs of market stress or a change in fundamentals. The New Zealand dollar, for example, sharply deteriorated against the U.S. dollar during the summer as plunging dairy prices caused the nation’s current account gap to widen.
Investors can also take advantage of the market mispricing volatility by taking out put options as an inexpensive insurance policy against large market swings. For example, although the Mexican peso’s long-term prospects are positive given the country’s economic reform efforts, an out-of-the-money put option may be a good way of providing low-cost protection in the short term should there be a sudden decline in sentiment toward emerging markets in general.
DIVERSIFYING AWAY EQUITY VOLATILITY
It also should not be forgotten why investors seek exposure to fixed income: to gain diversification from equities. Figure 2 shows that lower-risk fixed income assets such as high-quality government bonds have lower or even negative correlation to equities. This inverse relationship helps to smooth a portfolio’s volatility during periods of equity market weakness. High yield and emerging market debt both have higher correlations to equities, but during times of market stress, they may not provide the same level of diversification as higher-quality fixed income assets.
Credit also has a higher correlation to equities than global sovereign bonds. It diversifies within fixed income, but not against equities. During periods of market stress, therefore, the ability of credit to diversify and protect capital is somewhat compromised. Investors with heavy allocations to credit may miss out on the defensive characteristics that a bond portfolio should typically provide during turbulent periods.
VOLATILITY IS NOT NECESSARILY YOUR ENEMY
Volatility is widely feared, but it does not need to be. To profit from volatility, however, investors should be prepared for the unexpected and able to react quickly to changing circumstances. Flexibility is also required to invest across markets and different types of bonds, on both the long and short side. Traditional approaches to fixed income market investing are often constrained by benchmarks that are dominated by the largest issuers of debt. Such approaches are unlikely to deliver optimal results, especially when interest rates are on the move. In a world of multi-speed economic growth and differing interest rate cycles, the ability to shift positions quickly can make a huge difference to performance.
It is important to stress that flexibility need not come at the expense of quality or bring additional transaction costs—it is possible to retain a high-quality, liquid profile while still being agile enough to manage risks. A portfolio that is not constrained by a benchmark, but still contains the best investment ideas, should fulfill fixed income’s role as a diversifier and a provider of sustainable income and capital preservation. Ultimately, the goal is balance: how to find the right mix between duration, country allocation, bottom-up security selection, and currency preservation to achieve optimal returns while effectively managing risk and protecting the portfolio.
FIGURE 2: Diversification should still be important for investors
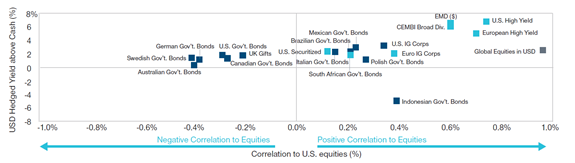
Sources: UBS, Barclays, J.P. Morgan, Bank of America/Merrill Lynch, S&P, MSCI, and T. Rowe Price. Yield shown is on a hedged basis in U.S. dollars. Volatility is based on the monthly returns each asset class hedged into U.S. dollars.
2015-GL-2675
重要情報
当資料は、ティー・ロウ・プライス・アソシエイツ・インクおよびその関係会社が情報提供等の目的で作成したものを、ティー・ロウ・プライス・ジャパン株式会社が翻訳したものであり、特定の運用商品を勧誘するものではありません。また、金融商品取引法に基づく開示書類ではありません。当資料における見解等は資料作成時点のものであり、将来事前の連絡なしに変更されることがあります。当資料はティー・ロウ・プライスの書面による同意のない限り他に転載することはできません。
資料内に記載されている個別銘柄につき、売買を推奨するものでも、将来の価格の上昇または下落を示唆するものでもありません。また、当社ファンド等における保有・非保有および将来の組入れまたは売却を示唆・保証するものでもありません。投資一任契約は、値動きのある有価証券等(外貨建て資産には為替変動リスクもあります)を投資対象としているため、お客様の資産が当初の投資元本を割り込み損失が生じることがあります。
当社の運用戦略では時価資産残高に対し、一定の金額までを区切りとして最高1.265%(消費税10%込み)の逓減的報酬料率を適用いたします。また、運用報酬の他に、組入有価証券の売買委託手数料等の費用も発生しますが、運用内容等によって変動しますので、事前に上限額または合計額を表示できません。詳しくは契約締結前交付書面をご覧ください。
「T. ROWE PRICE, INVEST WITH CONFIDENCE」および大角羊のデザインは、ティー・ロウ・プライス・グループ、インクの商標または登録商標です。
ティー・ロウ・プライス・ジャパン株式会社
金融商品取引業者関東財務局長(金商)第3043号
加入協会:一般社団法人日本投資顧問業協会/一般社団法人投資信託協会


