

Emerging Markets Local Currency Bonds: Opportunities to Gain Yield and Time
EXECUTIVE SUMMARY
A traditional international bond portfolio that consists mostly of the largest debt issuers (i.e., developed market governments) has serious drawbacks in the current environment: Yield are minimal, and interest rate risk is high. At the same time, both emerging market (EM) local currency bonds and EM bonds denominated in U.S. dollars look relatively cheap versus developed markets.
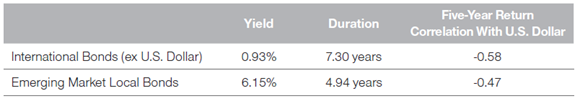
Importantly, investors with an international bond portfolio currently invested in only high-quality sovereigns are only receiving a yield of around 1% with a seven-year duration. Effectively, within the developed world, durations have lengthened while the amount of money received has lessened. By contrast, EM local investors are currently receiving a yield of around 6% with less than a five-year duration. That provides a solid starting point for investors who do not have particularly large investments in EM local but who have large international bond exposures.
For many emerging market (EM) debt investors, the last year or so has been a difficult period. However, the fundamentals remain strong, and there remains a compelling case for investors looking for a higher yield with less duration—a measure of a bond’s sensitivity to changes in interest rates.
LOOKING BACK TO LOOK FORWARD
Attracted by high yields and currency momentum, investors plowed into EM local funds following the 2008 financial crisis. These one-way flows suddenly reversed course in June 2013, when the “taper tantrum” hit a number of EM markets. This marked the start of an extended period of cash outflows from the asset class, which have only recently receded. At the same time, expectations for higher U.S. interest rates have fueled a rally in the U.S. dollar and a general retreat from EM currencies.
IS IT ALL ABOUT THE FED NOW?
The prospect of the U.S. Federal Reserve (Fed) hiking rates has made investors cautious about EM assets in general. When it happens, it is likely to lead to tighter liquidity conditions. However, with both Japan and Europe having eased monetary policy since 2013, this should help provide a palliative to EMs importing capital.
Much of the concern during the taper tantrum centered on whether EM policymakers would act in an appropriate manner. While the policy action has varied country by country, there are good reasons to believe that many EM policymakers are aware of the actions needed. Indeed, the likes of India and Indonesia have surprised with their reform programs and the balanced approach they have taken in attracting and retaining global capital. Moreover, with lower inflationary pressures, cheaper currencies, and better fiscal positions, the conditions for a taper/tightening tantrum this time seem less obvious.
DISPERSION WILL REMAIN TO THE FORE
Last year we saw widespread dispersion in the performance of individual countries within the EM universe. The disparate trend seems likely to persist this year, although probably not to such an extreme degree. Reinforcing the pattern, there are a number of countries at different stages of the economic and interest rate cycle. Some Asian markets such as India, Indonesia, Sri Lanka, and the Philippines are recording economic growth rates in excess of 5%, while a number of European and Latin American economies are running at a more subdued pace. Indeed, recessionary growth prints in two of the largest markets—Brazil and Russia—will suppress overall EM growth this year.
Meanwhile, a continued easing in the pace of growth in China will also have a negative impact on countries that are major commodity exporters. Such is the rerating of China’s growth over the past five years that India’s growth rate may well surpass China’s over the next year or two as India continues on its reform path. In spite of this baton change, the importance of China remains substantive. China is still five times the size of India, so at an aggregate level, the slowdown in China will still be a headwind globally and for EMs.
We believe that currencies are likely to remain a performance headwind in the near term, but this should gradually subside as the year progresses. While history shows that U.S. dollar strength can persist for long periods, it has already made a significant move to the upside. Additionally, it seems unlikely that U.S. growth will witness the strong levels associated with the late 1990s technology boom (which drove U.S. dollar strength to levels not seen again until recently). In part, a protracted period of unilateral dollar strength seems less plausible in an increasingly intertwined global economy. Rampant dollar strength combined with weakness abroad would eventually weigh on the U.S. economy and, as a consequence, the strong dollar dynamic.
Meanwhile, given the bias of yields to trend higher in developed markets (DMs), the likelihood of further yield compression in EM local as an overall asset class is relatively low. Dispersion in yield moves will likely remain high, however, supporting active management.
AN ATTRACTIVE ASSET CLASS FOR GLOBAL DIVERSIFICATION
With U.S. Treasury yields likely to rise from low levels and negligible yields on offer in Europe and Japan, investors across DMs have substantial incentive to diversify globally. However, a traditional international bond portfolio that consists mostly of the largest debt issuers (developed market governments) has serious drawbacks in the current environment: Yields are minimal, and interest rate risk is high.
Based on the yield and duration data in Figure 1, an EM local portfolio may offer a more attractive value proposition in comparison with international bonds, as the combination of higher yield and lower duration may provide better protection against rising rates in the medium term.
FIGURE 1: EM local bonds offer higher yields with shorter durations
As of 27 February 2015
Sources: Barclays, J.P. Morgan, and T. Rowe PriceInternational
Bonds Benchmark: Barclays Global Aggregate ex USD Index
EM Local Index: JP Morgan GBI-EM Global Diversified Index
Additionally, both asset classes demonstrate a similar negative correlation to the U.S. dollar over the past five years. In a world where the dollar is likely to remain relatively well supported, EM local debt could prove a useful destination for diversifying international debt allocations.
Given that durations of international bond portfolios have risen as interest rates have fallen, investors are effectively waiting longer for less. Diversifying into EM local bond markets helps redress this trend. Additionally, studies suggest that many investors tend to have relatively low allocations to EM debt opportunities but can often have large international bond exposures. This suggests that investors’ capacity to allocate more to EM local debt markets remains high.
Last, valuations have also broadly cheapened over the past two years. This is particularly so on the foreign exchange side, where a number of currencies are trading at all-time lows versus the U.S. dollar. Similarly, as investors have raised risk premia required on EM assets, both EM local currency bonds and EM bonds denominated in U.S. dollars look relatively cheap versus DMs.
Importantly, long-term fundamental drivers in emerging markets debt remain sound, with solid sovereign balance sheets and higher growth profiles relative to DMs over the medium term. Additionally, the opportunity set available to investors continues to grow; a positive for investors wishing to gain access to this diverse asset class. Although the prospect of the Fed raising interest rates later this year has the potential to increase volatility in the coming months, from a medium-term perspective, this should provide a good opportunity for clients to accumulate EM local allocations.
2015-GL-1993
重要情報
当資料は、ティー・ロウ・プライス・アソシエイツ・インクおよびその関係会社が情報提供等の目的で作成したものを、ティー・ロウ・プライス・ジャパン株式会社が翻訳したものであり、特定の運用商品を勧誘するものではありません。また、金融商品取引法に基づく開示書類ではありません。当資料における見解等は資料作成時点のものであり、将来事前の連絡なしに変更されることがあります。当資料はティー・ロウ・プライスの書面による同意のない限り他に転載することはできません。
資料内に記載されている個別銘柄につき、売買を推奨するものでも、将来の価格の上昇または下落を示唆するものでもありません。また、当社ファンド等における保有・非保有および将来の組入れまたは売却を示唆・保証するものでもありません。投資一任契約は、値動きのある有価証券等(外貨建て資産には為替変動リスクもあります)を投資対象としているため、お客様の資産が当初の投資元本を割り込み損失が生じることがあります。
当社の運用戦略では時価資産残高に対し、一定の金額までを区切りとして最高1.265%(消費税10%込み)の逓減的報酬料率を適用いたします。また、運用報酬の他に、組入有価証券の売買委託手数料等の費用も発生しますが、運用内容等によって変動しますので、事前に上限額または合計額を表示できません。詳しくは契約締結前交付書面をご覧ください。
「T. ROWE PRICE, INVEST WITH CONFIDENCE」および大角羊のデザインは、ティー・ロウ・プライス・グループ、インクの商標または登録商標です。
ティー・ロウ・プライス・ジャパン株式会社
金融商品取引業者関東財務局長(金商)第3043号
加入協会:一般社団法人日本投資顧問業協会/一般社団法人投資信託協会
