September 2026
Global Asset Allocation Viewpoints
Welcome to our latest Asset Allocation Viewpoints - your monthly source for actionable insights on portfolio positioning from our Asset Allocation Committee and Multi-Asset team.
Outlook
- Markets have remained resilient, supported by strong and broadening corporate earnings and sustained AI-related investment, although elevated valuations and geopolitical uncertainty remain sources of volatility.
- The global economy remains supported by technology investment and fiscal spending, though growth is increasingly uneven across regions as higher energy costs, interest rates, and geopolitical uncertainty create divergent pressures.
- The policy outlook remains highly data dependent as central banks balance persistent inflation pressures against resilient growth, while fiscal concerns and strong investment demand are contributing to upward pressure on longer-term yields.
- Key risks include renewed geopolitical escalation and commodity price volatility, persistent inflation and higher interest rates, earnings sustainability, and signs of deterioration in labor markets.
Themes Driving Positioning
A Broader Earnings Engine
The latest earnings season provided compelling evidence that the profit cycle is broadening. Results were strong across the market, with roughly 78% of S&P 500 companies beating earnings estimates and positive revisions spreading across industries. Those beats are lifting 2026 earnings expectations, yet 2027 estimates continue to rise and still imply robust growth—an encouraging sign that earnings momentum is strengthening even off a higher base. Recent market behavior offers another encouraging signal. Despite a de-rating in parts of the AI complex, broader markets proved resilient as strength elsewhere helped pick up the slack. AI remains an important earnings driver, with hyperscaler results reinforcing the investment runway, but it no longer needs to carry the market alone. Robust M&A and healthy capital markets provide additional support. This increasingly diversified earnings backdrop reinforces our constructive view on equities, while elevated valuations and expectations argue for selectivity and disciplined positioning.
A Higher Bar, Still Higher Earnings1
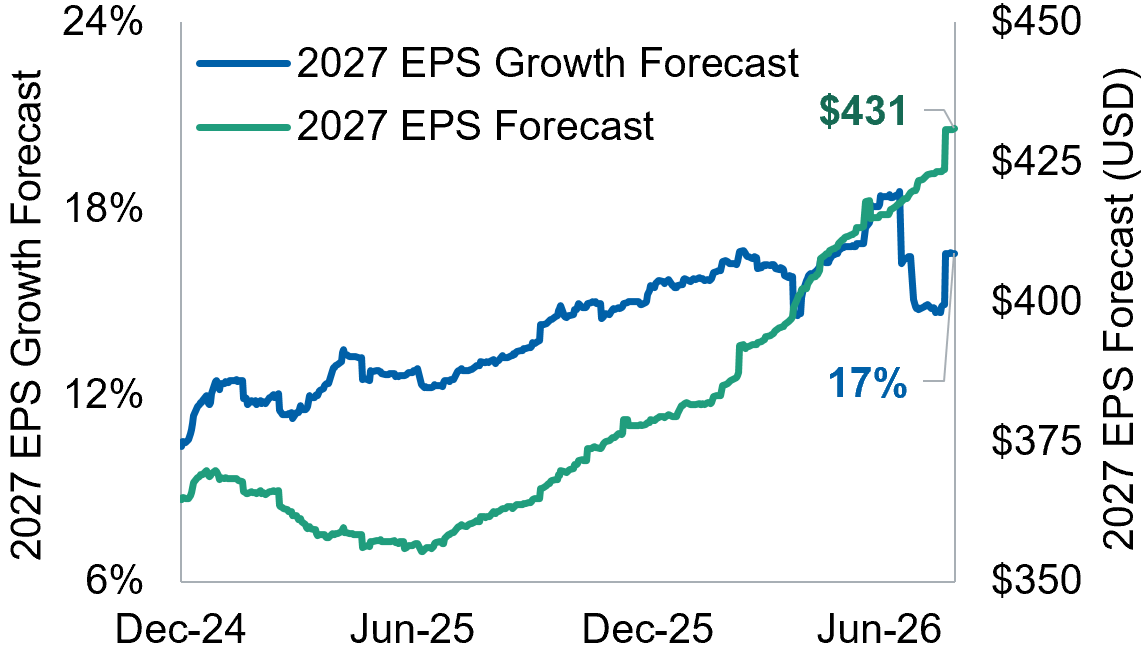
Data as of 31 August 2026 unless otherwise noted. There is no guarantee that any forecast made will come to pass.
1Source: FactSet and FTSE Russell. Data is represented by the Russell 3000 Index. Please see additional disclosures for more information.
Emerging Markets’ Next Act
We recently increased our overweight to emerging market (EM) equities as improving fundamentals converge with compelling valuations. Following the recent sell-off, some froth has come out of EM markets, while earnings remain supportive. At roughly 10x forward earnings versus more than 15x for developed markets, EM offers an increasingly attractive entry point. Importantly, the opportunity is extending beyond the technology story we previously highlighted. Broader capital spending on infrastructure, manufacturing, energy security and digital capacity is creating new sources of growth, while AI infrastructure remains an important tailwind in Taiwan and Korea. A weaker U.S. dollar could provide another boost by easing financial conditions and supporting capital flows, with persistent U.S. fiscal deficits reinforcing our expectation for intermediate-term dollar weakness. Together, solid earnings, expanding investment and attractive valuations provide a more diversified foundation for EM returns, supporting our overweight while remaining mindful of technology concentration, cyclical risks and elevated energy prices.
A Wider Gap, A Bigger Opportunity2
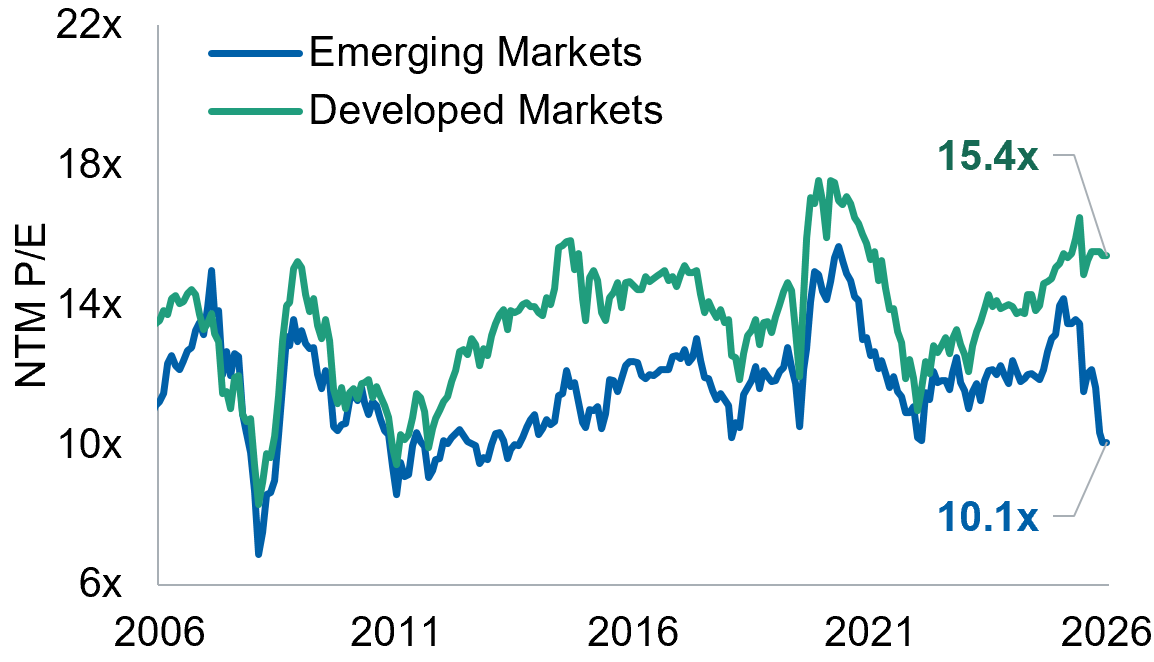
Data as of 31 August 2026 unless otherwise noted. There is no guarantee that any forecast made will come to pass.
2Sources: FactSet and MSCI. Emerging and Developed Markets data is represented by the MSCI Emerging Markets and MSCI EAFE indices, respectively. Please see additional disclosures for more information.
Asset Class Positioning
These views are informed by a subjective assessment of the relative attractiveness of asset classes and subclasses over a 6- to 18-month horizon.

Asset Classes
- We maintain a modest overweight to equities, supported by broadening corporate earnings momentum, resilient economic growth, and continued tailwinds from AI-related investment, while elevated valuations and higher interest rates warrant some caution.
- Within equities, we continue to favor U.S. growth, emerging markets, and small-cap stocks.
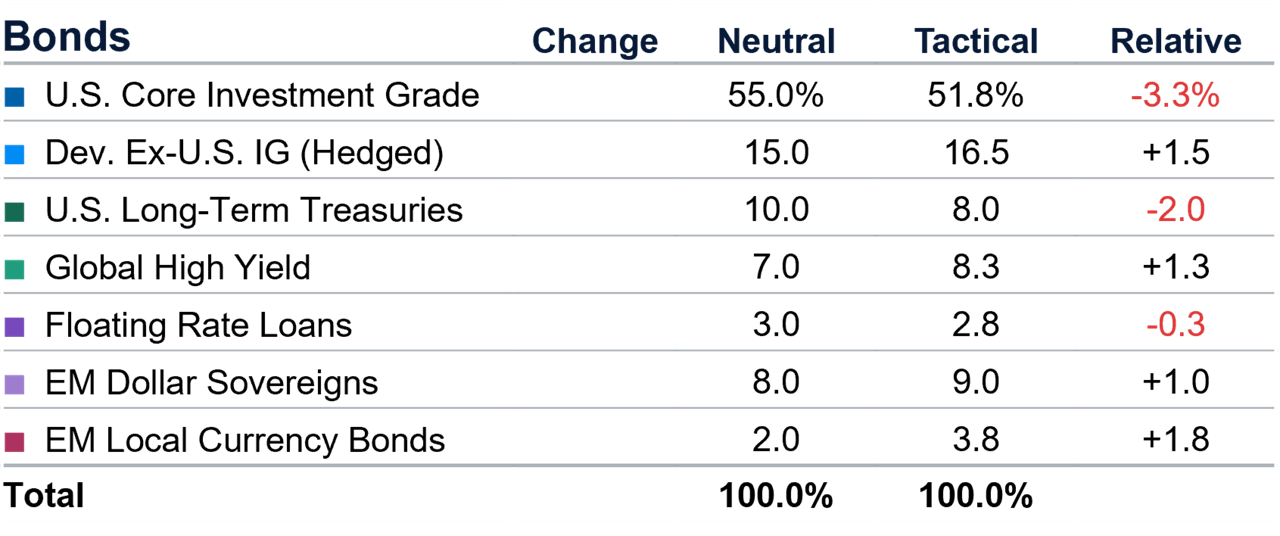
- We remain underweight bonds and maintain a cautious stance on duration, reflected through underweights to long-term U.S. Treasuries and Core bonds, as resilient growth, inflation uncertainty and fiscal pressures keep upward pressure on longer-term yields.
- We maintain a long position in short-term TIPS for inflation mitigation and remain constructive on high yield given healthy fundamentals, attractive income and its relatively short-duration profile.
- Cash yields remain reasonably attractive, but we maintain a neutral position as short-term bonds continue to offer somewhat more attractive income opportunities.
Equities
Regional Views
Broadening earnings strength, AI-related investment and robust M&A activity support fundamentals. Higher interest rates along with political and inflation uncertainty remain key risks.
Fiscal expansion and improving manufacturing support the outlook, but modest growth, higher energy costs and tighter monetary policy continue to constrain the upside.
Attractive valuations and healthy earnings remain supportive, while fiscal concerns, inflation and policy uncertainty continue to weigh on sentiment.
Fiscal stimulus, capital spending and improving earnings revisions remain supportive, while tighter monetary policy, higher rates and elevated valuations present an offsetting risk.
Fundamentals strong and accelerating. Energy and materials exposure cushions inflation. Tariff escalation likely to be a manageable risk.
Commodity exposure remains supportive, but recent policy changes affecting residential property and financials have weakened the relative outlook.
Compelling valuations, supportive earnings and continued AI-infrastructure investment strengthen the outlook, while technology concentration and sensitivity to the global semiconductor cycle remain key risks.
Policy support and anti-involution efforts may improve corporate margins, but persistent housing weakness and soft domestic demand are likely to keep the recovery uneven.
Style & Capitalization Views
Earnings growth is exceptional, supported by continued AI investment and adoption. Improved relative valuations are supportive, though elevated expectations and questions around the returns on AI capex remain risks.
Broadening earnings and cyclical strength remain supportive, including some beneficiaries of AI investment. However, valuations have become less compelling.
Valuations remain relatively expensive, while earnings growth is less compelling than in U.S. Growth. Higher energy costs and limited AI exposure also constrain the outlook.
Attractive valuations and fiscal support remain constructive, particularly for financials and industrials. Higher energy costs and tighter monetary policy remain risks.
Fundamentals remain very strong and are broadening outside mega-cap leaders, but elevated valuations and expectations leave less room for disappointment.
Mid-caps have seen an influx of AI infrastructure capex beneficiaries. Broadening growth and capital spending support the outlook.
Broadening growth, fair valuations and capital-markets activity remain supportive. Higher rates remain the key risk for smaller, more leveraged companies.
Fiscal stimulus in Europe and Japan remains supportive, but higher energy costs, tighter policy, higher interest rates and modest growth constrain the outlook.
Attractive valuations and fiscal support remain constructive as earnings broaden. The sector also offers more idiosyncratic opportunities outside large-cap markets.
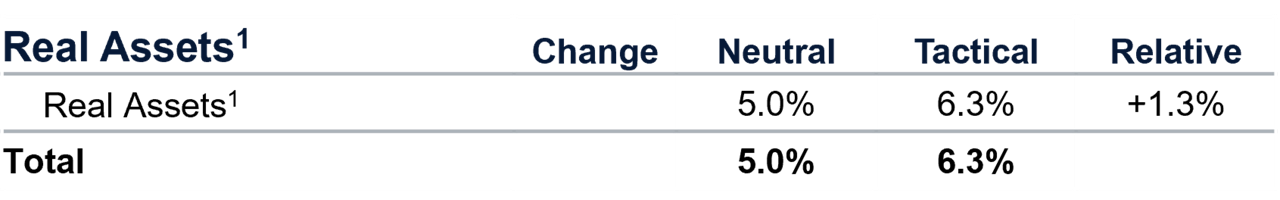
Real assets remain supported by dollar debasement concerns, AI-related infrastructure demand, and supply constraints. A more-hawkish Fed could be a headwind.
Bonds
Regional & Sector Views
Yields attractive and credit fundamentals supportive, but tight spreads and continued upward pressure on longer-term rates from resilient growth, inflation and fiscal concerns warrant a cautious stance.
Attractive yield levels remain supportive, though higher energy costs and tighter monetary policy in several developed markets could keep rate volatility elevated.
Upward pressure on long-term yields may persist as resilient nominal growth, inflation risks and heavy fiscal funding needs keep term premiums elevated.
Inflation pressures have moderated from their highs, but energy and refined-product risks could still generate renewed near-term price pressures, supporting continued inflation protection.
Healthy fundamentals, attractive income and a relatively short-duration profile remain supportive, though tight spreads and rising data-center issuance may limit further upside.
Yields remain attractive, but persistent challenges in software—the largest source of spread pressure in the asset class—and tight overall valuations continue to limit the upside.
Attractive yields and generally supportive fundamentals remain constructive, although higher U.S. rates and geopolitical risks could contribute to volatility.
Compelling yields remain supportive, while local currencies could benefit from an eventual softer U.S. dollar; elevated global rates remain a near-term risk.

Asset Allocation Viewpoints Webcast
Tune in. Take away actionable insights—direct from our top multi-asset experts.
Portfolio Implementation
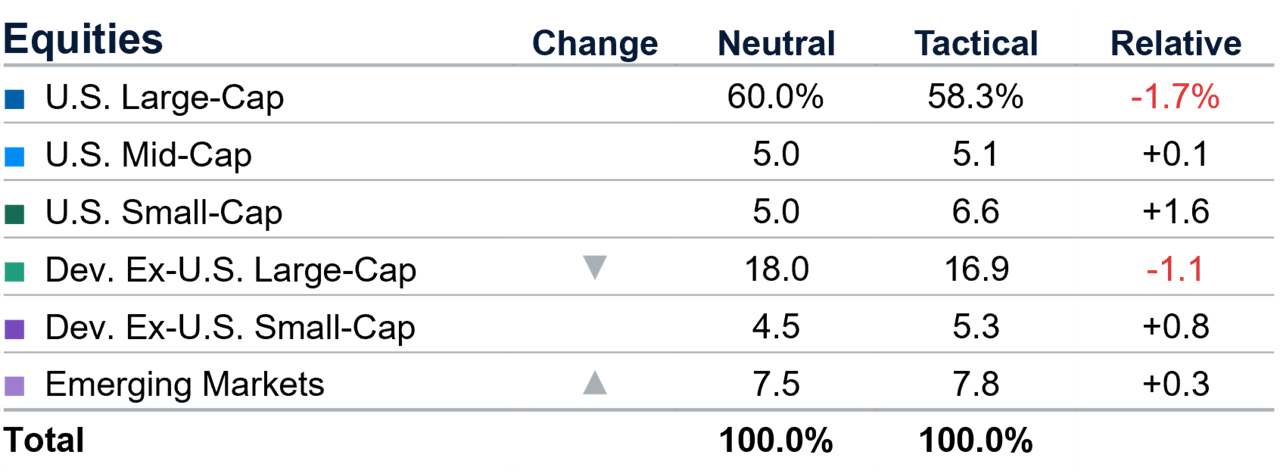
Equity
Tactical Allocation Weights

Bonds
Tactical Allocation Weights

ADDITIONAL DISCLOSURES
1 Real Assets allocation is representative as a percentage of the overall equity allocation.
Source: T. Rowe Price. Unless otherwise stated, all market data are sourced from FactSet. Copyright 2026 FactSet. All Rights Reserved.
These are subject to change without further notice. Figures may not total due to rounding.
Neutral equity portfolio weights are representative of a U.S.-biased portfolio with a 70% U.S. and 30% international allocation; includes allocation to real assets equities. Core fixed income allocation is representative of a U.S.-biased portfolio with 55% allocation to U.S. investment grade.
S&P, MSCI and FactSet do not accept any liability for any errors or omissions in the indexes or data, and hereby expressly disclaim all warranties of originality, accuracy, completeness, timeliness, merchantability, and fitness for a particular purpose. No party may rely on any indexes or data contained in this communication. Visit www.troweprice.com/marketdata for additional legal notices & disclaimers.
IMPORTANT INFORMATION
This material is being furnished for general informational and/or marketing purposes only. The material does not constitute or undertake to give advice of any nature, including fiduciary investment advice. Prospective investors are recommended to seek independent legal, financial and tax advice before making any investment decision. T. Rowe Price group of companies including T. Rowe Price Associates, Inc. and/or its affiliates receive revenue from T. Rowe Price investment products and services. Past performance is not a guarantee or a reliable indicator of future results.
This information is not intended to reflect a current or past recommendation concerning investments, investment strategies, or account types, advice of any kind, or a solicitation of an offer to buy or sell any securities or investment services. The opinions and commentary provided do not take into account the investment objectives or financial situation of any particular investor or class of investor. Please consider your own circumstances before making an investment decision.
Information and opinions presented have been obtained or derived from sources believed to be reliable and current; however, we cannot guarantee the sources’ accuracy or completeness. There is no guarantee that any forecasts made will come to pass. The views contained herein are as of the date noted on the material and are subject to change without notice; these views may differ from those of other T. Rowe Price group companies and/or associates. Under no circumstances should the material, in whole or in part, be copied or redistributed without consent from T. Rowe Price.
Risks: All investments are subject to risk, including possible loss of principal. Stock prices can fall because of weakness in the broad market, a particular industry, or specific holdings. Fixed-income securities are subject to credit risk, liquidity risk, call risk, and interest- rate risk. As interest rates rise, bond prices generally fall. Diversification does not assure a profit or protect against a loss in a declining market.
USA: T. Rowe Price Investment Services, Inc., and T. Rowe Price Associates, Inc.
© 2026 T. Rowe Price. All Rights Reserved. T. ROWE PRICE, INVEST WITH CONFIDENCE, the Bighorn Sheep design and related indicators (see troweprice.com/ip) are trademarks of T. Rowe Price Group, Inc. All other trademarks are the property of their respective owners. Use does not imply endorsement, sponsorship, or affiliation of T. Rowe Price with any of the trademark owners.
202609-5899555