

 Oak Hill Advisors (OHA)
A Leading Global Alternative Credit asset manager

OHA is a trusted partner to many of the world's largest and most sophisticated investors, specialising in alternative global credit strategies.
Sep 2026
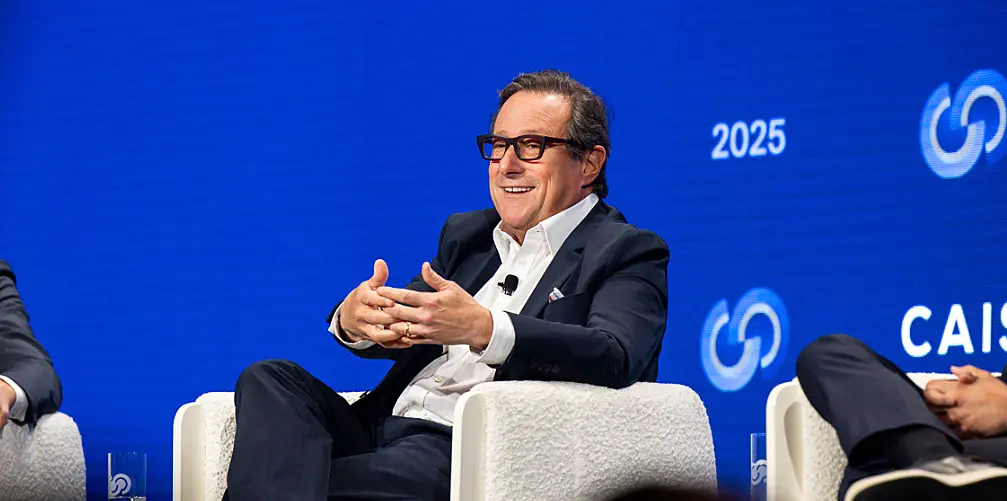
Meet the investor trusted by the world's biggest pools of capital
The world's biggest sovereign wealth and pension funds entrust billions to Glenn August, Founder and CEO of Oak Hill Advisors. Here's what his 39 years in credit have taught him.
Multi-strategy credit investment solution
Watch this video to learn how OFLEX AUD leverages OHA’s alternative credit investment platform and T. Rowe Price’s exceptional client service to deliver an flexible solution.
OHA has over 30 years of experience investing as a specialist in the alternative credit markets, and T. Rowe Price has a long, successful history of delivering investment solutions for clients to help achieve their financial goals.
Together, through our partnership, OHA and T. Rowe Price seek to bring institutional quality alternative credit solutions to individual investors, leveraging our complementary strengths and investment management and client experience.
As we continue to build new products to help clients address their investment goals, we are excited to introduce the T Rowe Price OHA Flexible Credit Income Fund, or OFLEX AUD.
OFLEX AUD is a semi‑liquid interval fund which seeks to capitalise on OHA’s best ideas across our multi‑strategy credit investment platform.
Multi‑strategy credit investing has been core to OHA’s DNA since inception. For over three decades, we’ve invested capital dynamically in diverse credit asset classes on behalf of global institutional investors.
OFLEX AUD is built as an all‑weather strategy for individual investors, with flexibility to invest across global credit asset classes through evolving market conditions.
OFLEX AUD employs OHA’s consistent investment process to pursue opportunities across capital structures in both the liquid and private markets, with a rigorous focus on risk management.
OFLEX AUD seeks stable, income‑generating investments with resilient cash‑flow profiles across six sub‑strategies: direct lending, junior capital solutions, asset‑based lending, structured credit, special situations, and liquid credit.
Together, these strategies enable a flexible multi‑strategy approach to seek to capture attractive absolute and relative value.
OHA believes managers with the capabilities required to invest across the full spectrum of credit opportunities are better positioned to deliver attractive risk‑adjusted returns.
Choosing the right investment manager is a critical decision, particularly in private assets, for long‑term investment horizons.
We believe our industry specialist model and rigorous underwriting approach helps enhance alpha generation by leveraging capabilities from OHA’s entire integrated platform.
OFLEX AUD offers a single point of entry into the alternative credit markets that harnesses OHA’s robust capabilities and deep experience.
We look forward to the opportunity to partner with you on OFLEX AUD.
Thank you.
I’m Glenn August, founder and CEO of OHA.
Key Risks
The following risks are materially relevant to the Fund.
- Withdrawal Risk
- Reliance on the Underlying Fund
- Distribution Risk
- Foreign Investment Risk
- Liquidity Risk and Liquidity Management Risk
- Non-Compliance with Section 12(d) (1)(E) of the Investment Company Risk
- Credit Investment Risk
- Inflation Risk
- Interest Rate Risk
- Valuation Risk
End Note
OFLEX AUD seeks to provide the same type of private credit investment solution to individual investors that were previously largely only available to OHA’s institutional clients. Institutional clients may invest in products on substantially different terms and conditions than those offered by OFLEX AUD.
Why T. Rowe Price OHA Flexible Credit Income Fund (OFLEX AUD)?
APIR CHN4354AU | ARSN 690 410 176
The T. Rowe Price OHA Flexible Credit Income Fund AUD (OFLEX AUD or Fund) seeks to deliver an institutional-quality1 opportunistic multi-strategy credit solution for income-focused investors.
One-stop shop alternative credit strategy
A single-entry point into differentiated sources of income across private and public credit markets
Monthly income stream
Focus on regular, income-generating investments with resilient cash flow profiles that offer natural risk management characteristics
Distribution payments are not guaranteed.
Flexible investment strategy
Nimble, tactical approach with the ability to move quickly across credit markets to seize on periods of market volatility
The Genium rating (assigned March 2026) presented in this document is issued by Genium Investment Partners Pty Ltd ABN 13 165 099 785, which is a Corporate Authorised Representative of Genium Advisory Services Pty Ltd ABN 94 304 403 582, AFSL 246580. The Rating is limited to “General Advice” (s766B Corporations Act 2001 (Cth)) and has been prepared without taking into account the objectives, financial situation or needs of any individual, including target markets of financial products, where applicable, and is subject to change at any time without notice. Past performance information is for illustrative purposes only and is not indicative of future performance. It is not a recommendation to purchase, sell or hold the relevant product(s). Investors should seek independent financial advice before making an investment decision in relation to this financial product(s). Genium receives a fee from the Fund Manager for researching and rating the product(s). Visit Geniumip.com.au for information regarding Genium’s Ratings methodology.
The report that included the rating was published by Lonsec Research Pty Ltd ABN 11 151 658 561 AFSL 421 445 (Lonsec) for CHN4354AU on 13/05/2026. Lonsec receives a fee from fund managers for the preparation of reports. The report / rating is general advice only. An investor should be aware that: a) the advice has been prepared without taking into account an investors’ objectives, financial situation or needs; b) an investor should consider the appropriateness of the advice having regard to their own objectives, financial situation or needs before acting on the advice; and c) an investor should obtain a PDS relating to the product, consider the PDS and seek independent financial advice before making any decision about whether to acquire the product. The rating is not a recommendation to purchase, sell or hold any product. Past performance is not a reliable indicator of future Performance. Ratings are prepared based on information available at the time of preparation and may be subject to change by Lonsec without notice. Visit lonsec.com.au for important documents (FSG, Conflicts Statement). © 2026 Lonsec. All rights reserved.
About the Fund
| Investment Objective and Strategy of the Fund | The Fund seeks to provide income by investing substantially all of its assets in a USD-denominated share class of the Underlying Fund, which invests across a wide range of credit strategies. |
| Return Objective & Income Targets | Net Levered Return Objective: 10-12% Target Income Distributions: 8-10% Return objectives and income targets are not forecasts and are not guaranteed. Actual outcomes may differ materially. |
| Minimum Initial Investment (Fund) | A$100,000 |
| Distributions & Reinvestment (Fund) | Monthly (when applicable or available from the Underlying Fund) Distributions will be paid to investors in cash or reinvested |
| Unit Price / NAV Frequency (Fund) | Monthly |
| Applications (Fund) | Monthly |
| Redemptions (Fund) | Monthly. CIML retains discretion to accept or reject redemption requests. |
| Management fees and costs | The management fees and costs of the Fund are estimated to be 1.33% per annum of the net asset value ('NAV' or 'net asset value') of the Fund. The Underlying Fund Investment Adviser has waived its entitlement to this management fee for all periods up to and including the period ending on 31 December 2026. Following the expiry or withdrawal of the waiver, the Underlying Fund management fee of 1.00% per annum will become payable. Investors should not assume that the waiver will be extended beyond the current waiver period. Full details of other fees and charges are available within the Fund’s Product Disclosure Statement and Reference Guide. |
| Risk | The following risks are materially relevant to the Fund.
|

We're inviting investors to register their interest in our initial offer. Click the button below to sign up.
Fund literature

Please refer to the Fund’s product disclosure statement for more information.
How does OFLEX AUD invest across credit markets?
Click the strategy name to learn more about OFLEX AUD's portfolio mix and opportunity set.

Direct lending
Primarily focused on directly originated and customized private financing solutions, focused on “large cap” senior secured direct lending, including first lien senior secured loans and unitranche loans.
The Underlying Fund is generally expected to invest over time within the above indicative allocation ranges (20% to 50%).

Junior capital solutions
Focused on junior parts of the capital structure, primarily second lien loans, subordinated debt and preferred equity.
The Underlying Fund is generally expected to invest over time within the above indicative allocation ranges (0% to 30%).

Liquid credit
Idiosyncratic credit selection within high yield bonds and leveraged loans.
The Underlying Fund is generally expected to invest over time within the above indicative allocation ranges (0% to 30%).

Special situations
Focused on companies experiencing financial or operational challenges, providing liquidity solutions, bridge capital and through secondary trading.
The Underlying Fund is generally expected to invest over time within the above indicative allocation ranges (0% to 30%).

Real asset lending
Focused on providing directly originated and privately negotiated capital solutions for real assets primarily within the infrastructure, shipping, aviation and telecommunications categories.
The Underlying Fund is generally expected to invest over time within the above indicative allocation ranges (0% to 30%).

CLOs/structured credit
Primarily collateralised loan obligations (“CLOs”), including the debt and equity tranches of CLOs that are backed by senior secured corporate loans made to companies operating primarily in the U.S. or Europe, sourced from the secondary market.
The Underlying Fund is generally expected to invest over time within the above indicative allocation ranges (0% to 30%).
As at 30 June 2026. The Underlying Fund may also invest in additional strategies in the future. There is no guarantee allocations will be maintained.
OHA's compelling track record across decades
With over 30 years of experience navigating market cycles, OHA's disciplined approach centers on deep research, patience, and a partnership mindset. OHA's priority is to preserve and grow client capital, whatever the market environment.
Over
30 years
History through market cycles
With
US$112bn
Assets under management2
Over
25 years
Average investment team tenure
Over
130
Investment professionals
With
7
Offices globally
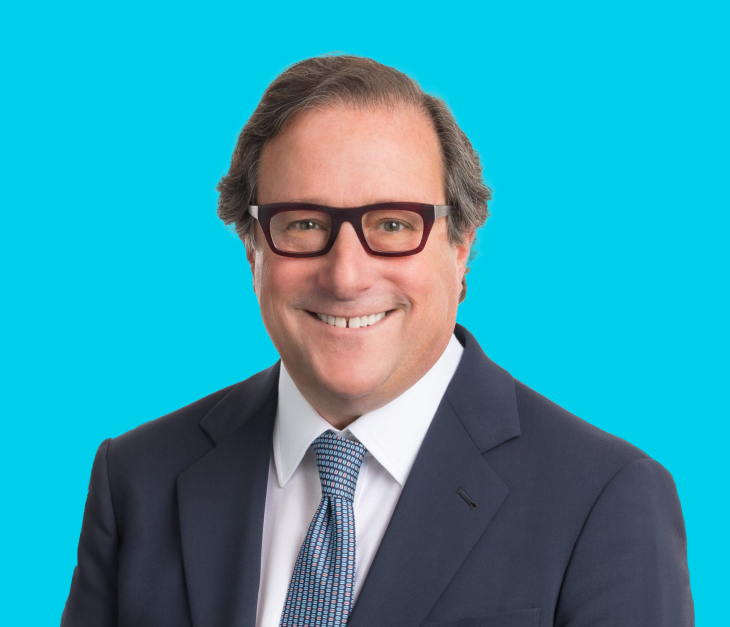
Meet our Australian OHA team
Adam Nankervis
Portfolio Manager & Partner
Adam shares portfolio management responsibilities for a number of OHA’s portfolios. Mr. Nankervis serves on the firm’s new product and business activity committee.
Adam is based in Melbourne and has 17 years of investment experience.
Nicholas Tsoumanis
Principal
Nicholas works in the areas of investor relations and new business development in the Sydney office. Prior to OHA, Nicholas worked as a Research Analyst at Perpetual Limited across their equity and alternative multi-manager investment programs.
Nicholas is based in Sydney.
Insights from the experts
Timely credit market perspectives and practical insights, helping advisers make informed decisions for their clients.
Mar 2026
Adam Nankervis on multi-asset credit investing
Adam shares his perspectives on where he sees opportunities and risks in alternative credit and explains how a multi-asset credit approach enables investors to capture relative value and effectively navigate the evolving market conditions.
I'm joined today by Adam Nankervis, portfolio manager and partner at Oak Hill Advisors.
Adam is among the incredible investors sharing insights at the Family Office Investment Forum in Sydney today.
Welcome Adam.
It's great to have you with us.
Thanks for having me, Zelda.
How have private credit markets evolved in recent years?
Credit markets?
Have you got to look at private credit in the context of the evolution of the high yield market, the leveraged loan market and private credit?
And for many decades, it was the high yield market and leveraged loan market that was used for M&A and there was a real pull of demand the private equity stepped into post the global financial crisis.
And so it sort of offers an ability for diligence process to be more resilient, direct negotiation of terms and sort of speed of execution also.
And so there's a natural point where now, you know, it forms part of the financing market alongside high yield and leveraged loans.
And I don't think you can look at it in isolation.
Can you explain how private credit markets crossover and interact with the high yield and leveraged loan markets?
Private equity is really sophisticated and so by former colleagues at Credit Suisse, you know they sit at different private equity firms as an instance and they're looking for best execution for their investors.
And now the private credit is into the mid to large cap of 75102 hundred 500 million EBDA type context is they can access both markets.
And So what we see is a lot of lenders moving in and out of the syndicated markets, the private credit markets and sometimes into the asset backed market also.
And so there's a real sort of interaction of lenders as you move through the different markets over time.
What does the interaction and crossover between private credit markets with the high yield and leveraged loan markets mean for investors and how can it benefit their portfolios?
I think it can benefit for a few reasons.
One, if you've got a manager who who's looking at both markets, they can get a real understanding of the businesses.
And so you know, when something moves into the private market, there's a good chance they will lend us to that business for for maybe 5-10 years prior.
And so there's a real ability to have a history and diligence.
I think the other benefit by being in both is your flows can can ebb and flow where sometimes there might be better risk adjusted returns in one market and sometimes there might be a better risk adjusted returns in the other.
And that that's hard to predict over time.
By looking at both, you can sort of construct A portfolio that's going to get ultimately give you the best risk adjusted return.
What opportunities and risks are you seeing in alternative credit at the moment on the risk side, I think that, you know, the biggest one is, you know, the evolution of business models from the impact of artificial intelligence.
And that is something that is our investors are focused on.
We're very focused on and what that means for recovery rates, what that means for your underwriting and what that means in the margin of safety you need in order to give loans to these impacted industries or maybe secondary impacted industries because the evolution is moving pretty quickly.
And so that's the key risk side and that is that is underwriting risk, which you know, it's a focus now and it's always been a focus in credit.
I think about the opportunities, it's coming from a few different aspects.
1 is asset based lending.
There's a lot of capital being deployed in fibre data centres, a whole range of different end markets where strategic capital providers in credit can get really good risk adjusted returns recently, you know, potential.
You sort of want to go to where capital is flowing out of sometimes because it puts the opportunity set back in the lender.
So private credit will be an interesting evolution this year with some of the news flow that's been flowing through.
And then we're also seeing syndicated markets generally sell first, ask questions later.
And so there are pockets of opportunity where you know, business models are being sold down, but but ultimately, you know, they're being correlated with with poor businesses.
And so that volatility creates the opportunity set for an investor.
How does a multi asset credit approach to investing enable you to capture relative value and effectively navigate the evolving market environment?
Credit markets evolve pretty quickly.
If you if you go back to the impact of COVID at different points in time, you know, IG bonds were attractive at one point, rescue financing, private credit, there's been an opportunity to buy that will be higher yield bonds.
But it's hard to predict when that opportunity set is going to present itself.
And so multi asset credit allows a manager to pivot to the extent that that opportunity set presents.
It also allows the manager to not go after opportunities that is being flooded with capital.
By doing that, you can create a portfolio that ultimately has diversification and you know, good risk adjusted return, which is the ultimate goal.
Thank you, Adam when we need to leave it there and get back to the forum.
I really appreciate you sharing your expertise with us today and for being a part of Global Investment Institute's Family Office Investment Forum.
Thank you for having me.
 Oct 2026
Alternatives
Why Invest in Real Asset Credit?
Summary:
- Real asset credit includes financing solutions for mission-critical infrastructure assets which are essential to the operation of the broader economy.
- These include telecom, energy and transportation assets such as cell towers, power plants, ports, bridges, tunnels, data centers and fiber networks.Core real asset markets are undergoing a transformational investment cycle (e.g. AI, densification of telecom grids, increasing demand for power, midstream buildout, replacement of aging infrastructure).
- These large expenditures are creating funding gaps and attractive opportunities for real asset credit.
- OHA believes real asset credit offers investment features including low correlation, inflation protection, tangible collateral, contractual cash flows and structural protections which may provide attractive risk-adjusted returns.
 Jun 2026
Alternatives
5 Big Investor Questions and Key Takeaways
At OHA’s Annual Meeting in May, Founder & CEO Glenn August delivered a presentation in which he addressed key questions for investors regarding 1) “cockroach” concerns, 2) AI disruption, 3) the Iran War, 4) private credit health, and 5) the opportunity set.
Key takeaways
- Credit issues today are largely idiosyncratic rather than systemic.
- AI disruption, geopolitical tensions, and the interest rate outlook present material market uncertainty.
- Negative investor sentiment toward private credit is not supported by underlying fundamentals and market structure.
- Dispersion and idiosyncratic challenges across borrowers are expanding the opportunity set.
- A downside protection focus remains critical to navigating the current dynamic market environment.
Livewire: Fund in Focus
Key takeaways
- OHA leverages deep institutional expertise and a global platform to invest across the full spectrum of non-investment-grade credit.
- A disciplined, private equity-style approach drives rigorous underwriting and risk management across sectors and credit types..
- OFLEX AUD offers diversified, income-generating exposure to a diversified credit portfolio which includes global private credit, complementing domestic portfolios and reducing local risk.
The views and opinions expressed in the video are those of the Investment Professional at the time of the interview, 27 October 2025, and are subject to change without notice. It is not intended to be securities recommendation or statement of opinion intended to influence a person or persons in making a decision in relation to investment. The video is used with permission from Livewire.
Chris Conway
Hello and welcome to Livewire Fund in Focus.
My name is Chris Conway. Today I'm sitting down with Adam Nankervis from Oak Hill Advisors. Adam is going to be talking to us about the T. Rowe Price OHA Flexible Credit Income Fund, otherwise known as OFLEX.
Adam, thanks for sitting down with Livewire today.
Adam Nankervis
Thanks for having me, Chris.
Chris Conway
Can you just provide a brief introduction to your firm.
Adam Nankervis
We've been around for over 30 years and we're alternative credit investment specialists. We manage US dollars $98 billion in the credit space. And we've been doing that as the market has evolved. So syndicated loans, high yield, started out in special situations, distressed in the ‘90s, and have evolved with the asset-backed market. And also more recently with the evolution of private credit in the large cap space.
We're focused on developed markets in the US and developed markets in Europe also. We have 120 investment professionals, and really try to, you know, underwrite our businesses.
Chris Conway
Adam, what would you say if I had to ask you for one element, what’s unique about the way you invest?
Adam Nankervis
The one element I'd say is we're trying to keep a consistent underwriting process where we really take a private equity style lens to credit investing. And what that means is we really focus on getting the industries right, we structure around those components. So as, as portfolio companies move from syndicated markets to private markets, maybe they're stressed, maybe they're looking for asset backed in certain parts of their capital structure.
If you can have an consistent coverage and team who has a real lens of what they
like within that sector, you can ultimately minimise defaults and harvest what is the credit premium.
We also then supplement those with specialists in documentation, in sourcing, in special situations in distress.
We're really are one team in how we're trying to approach the broader credit universe.
Chris Conway
Just talk to me more about that, Adam, what is the opportunity that you've identified now in the private credit space?
Adam Nankervis
We're bringing to the market what is the best ideas fund of Oak Hill. As I mentioned before, US$98 billion broad platform across different credit spaces. And so we're trying to get assets to compete against each other to create a broad constructive portfolio.
We've sort of broken down the market in everything we do, but it's really in sort of six areas.
The first is direct lending, which we're sort of seeing 50% equity checks behind us, we'll be able to structure those documents.
Second is similar junior capital, a little bit higher risk during the capital structure but higher return in that regard.
Special situations, which as the market evolves and external shocks happen, we can take advantage of that market.
There is the asset backed market, where we're seeing that evolution happen before us in data centers, in telecommunications, fiber construction, cell towers, in transportation, in shipping, aviation, you know, across that lens on the asset backside.
And then we've got two liquid markets that we that we really follow in our platform. One is syndicated loan and high yield market and also structured credit.
And we're trying to use all of that lens to construct a broad diverse portfolio and a real best ideas for the Australian market.
Chris Conway
Just talk to me a little bit, Adam, you know, obviously it's multi-strategy and you've just laid out all the different buckets that you look at. Are they all growing, are they all, you know, is this why this is such a compelling opportunity now, because of the growth and the
money that's flowing into these opportunities?
Adam Nankervis
Yeah, it's a combination, the direct lending market's been growing for some time now. You know, that is more of an evolved sort of market at this point, still attractive, but they all grow episodically and it's hard to predict when they're gonna happen.
Obviously there's a lot of capital chasing asset backed type lending at this point. Also in relation to data centers and telecommunications like I mentioned, and that's evolving and growing.
I think stressed and sort of special situations component that can be a function of what happens with the economy over the next few years. And so that opportunity set develops and it's somewhat hard to predict.
The goal is to not try and make those calls, but sort of react to the opportunities as they present.
Chris Conway
You sort of touched on it there, what are some of the risks and then how do you manage them? Is it a matter of just pulling the right lever on those different options in the portfolio at the right time?
Adam Nankervis
The risk component comes down to underwriting. Ultimately, you can talk about credit spreads, you can talk about liquidity premiums, but it means nothing unless, you know, you get your money back after writing that loan.
And so what we're focused on is making sure our underwriting standards that we've kept for the last 30 years remain resilient and that process remains consistent.
And we're also aware of the evolving risks in the market, whether that's related to trade, change in immigration policies on the labour component, AI risk that can develop in different business models, and sort of stroke of the pen risk that you see within the governments, given what used to be more healthcare is a lot broader at the moment.
And so, you know, they are the risks and that's what we're focused on, and it's not really anything new, but it's something to be really cautious of.
Chris Conway
Adam, talk to me about what role your fund can play in an investor's portfolio.
Adam Nankervis
I think it's an important income generating fund, that's what we're focused on, particularly across the platform is income generating assets, and so to the extent, investors are looking for some diversification in that.
I think diversification of the credit market that we're operating in, it's a US$2.5 trillion dollar private credit market globally, and we're focused on the large cap lending side of things.
And so investors that are looking for, you know, credit portfolio that have similar characteristics in size and EBITDA to the ASX 200. This is a great exposure for them to get that.
I also think it's pretty attractive for, as an Australian investor looking to get diversification offshore in credit. You know, less correlation to construction, and less correlation to the Australian risk that can be all correlated to an extent.
Chris Conway
Adam, thanks so much for sitting down with Livewire and taking us through that.
Adam Nankervis
Thank you very much.
Chris Conway
If you enjoyed that fund in focus, why not give it a like and don't forget to follow our YouTube channel, we're adding lots of great content every single week.
 Feb 2026
Alternatives
Credit Investor’s Checklist
A practical framework for evaluating credit opportunities highlighting key factors investors may want to assess across structure, risk and return.
 Oct 2025
Alternatives
Multi-Strategy Credit: Mix, Match and Maximize
A multi-strategy investment approach to alternative credit is designed to capitalise on compelling opportunities and manage risk across the credit universe.
 Sep 2025
Alternatives
We Are Going to Need a Bigger Borrower
Discover why OHA believes larger borrowers offer investors a full-life spread premium over smaller borrowers.
Credit investment experience
With one integrated platform across public and private credit— spanning performing, opportunistic, and stressed situations—OHA allocates to the most compelling risk-adjusted opportunities as markets evolve.
OHA Portfolio Management Team
16
senior portfolio managers guiding investment decisions across credit strategies.
Trading, Execution and Documentation
14
professionals ensuring seamless market execution and disciplined processes.
Industry-aligned investment specialists
70
investment specialists bringing deep insight across 16 industries.
- Aerospace / Autos / Metal & Mining
- Building Materials / Homebuilding
- Media / Telecom
- Chemicals
- Paper & Packaging
- Energy & Power
- Gaming / Leisure
- Healthcare
- Industrials
- Insurance Brokers / Financial Services
- Lodging
- Real Estate
- Retail / Consumer Goods
- Services
- Software / Technology
- Transportation
Strategy Specialists
31
experts in private, distressed, structured, and real asset credit strategies.
- Performing credit
- Private credit
- Distressed credit
- Structured credit
- Real assets
As of 30 September 2025.
Adam Nankervis
Adam shares portfolio management responsibilities for a number of OHA’s portfolios. Mr. Nankervis serves on the firm’s new product and business activity committee. Previously, he had senior research responsibility for the paper and packaging, services, gaming, lodging and real estate industries. Adam previously worked at Credit Suisse in the Financial Sponsors Group in New York and in the Investment Banking Division in Sydney. He earned a Bachelor of Electrical Engineering (First Class Honors) and a Bachelor of Commerce from the University of Melbourne.
Adam is based in Melbourne and has 17 years of investment experience.
Nicholas Tsoumanis
Nicholas Tsoumanis works in the areas of investor relations and new business development in the Sydney office. Prior to OHA, Mr. Tsoumanis worked as a Research Analyst at Perpetual Limited across their equity and alternative multi-manager investment programs. He earned a Bachelor of Commerce, with distinction, in Finance, Marketing and Business Systems Implementation, and a Bachelor of Computing in Information Systems and Computer Science from Deakin University.
Nicholas is based in Sydney.
Frequently asked questions
How to invest
Who can invest in OFLEX AUD?
Investors who qualify as wholesale under the Corporations Act or retail investors who have received personal advice. Advised retail investors may only invest indirectly in the Fund.
How can eligible investors invest directly, i.e., not through IDPS (investor directed portfolio services)?
Eligible investors may apply online directly via https://www.channelcapital.com.au/invest
The online system is designed to streamline the application process by reducing paperwork, increasing efficiency, and supporting a smoother experience for both direct investors and advisers. With automated onboarding and instant AML/KYC*, applications can be completed securely.
Which platforms is OFLEX AUD available on?
Hub24 - IDPS
Netwealth - Private & Public Menu IDPS
About OFLEX AUD
What is the T. Rowe Price OHA Flexible Credit Income Fund AUD?
OFLEX AUD is an unlisted Australian unit trust (AUT) registered with ASIC as a managed investment scheme under the Corporations Act.
What is the Underlying Fund?
The Underlying Fund is a Delaware statutory trust that is registered under the Investment Company Act of 1940 (United States), as a non-diversified, closed-end management investment company that is operated as an interval fund.
How will the Fund manage liquidity?
The Fund is generally expected to maintain a minimal cash balance (0% to 5% of NAV) for operational purposes, with the Fund investing substantially all of its assets in the Underlying Fund.
With the majority of the return being income do you foresee the NAV to increase over time?
While we anticipate that the majority of the Fund’s returns will be generated from income, there is a small element of capital appreciation which could cause the Fund’s NAV to fluctuate over time. In addition, hedging activity may also impact the NAV, as gains or losses from currency hedges can contribute to fluctuations.
How often will investors receive a distribution / dividend?
The Underlying Fund expects to pay regular monthly distributions.
Distribution payments are not guaranteed and are subject to the Underlying Fund's board approval. The Underlying Fund may pay distributions from the sale of assets, offering proceeds, or borrowings. The payment of distributions is subject to the discretion of the Underlying Fund's Board of Directors and applicable legal restrictions, therefore there can be no assurance as to the amount or timing of any such distributions. Up to 100% of distributions may be funded by the reimbursement of certain expenses that are subject to repayment to the Adviser of the Underlying Fund. Such waivers and reimbursements by the Adviser may not continue in the future.
Will the Fund do any hedging or shorting?
The Fund intends to invest in a USD-denominated share class of the Underlying Fund, which will be hedged back into AUD at the Fund Level. The Fund will not engage in short selling and may use leverage and derivatives only for foreign exchange hedging.
How is leverage used? Is this at the fund level or individual security level?
Leverage is not used at the Fund level, only in the Underlying Fund (as described in the OFLEX section of FAQ). Leverage in the Underlying Fund will be used at the overall fund level, not individual asset level.
How many holdings should we expect in the Underlying Fund? What will the average position size be?
OHA anticipates the Underlying Fund will maintain an average position size of 1-3% positions across 100+ positions.
How often are redemptions processed?
Monthly.
Redemption requests for a month must be received by 12 noon (Sydney, New South Wales time) at least ten (10) Business Days prior to the last Calendar Day of that month.
CIML retains discretion to accept or reject redemption requests.
If a redemption request is fulfilled, when will cash be available to the investor?
Redemption requests will generally be processed as at the last calendar day of that month. Once CIML has effected the redemption of an Investor’s Units, the redemption proceeds will be paid within 10 Calendar Days.
If redemption requests exceed the Fund’s available cash, they may be partially fulfilled on a pro-rata basis, and any requests (not fulfilled in full) may be resubmitted for the next redemption date. Any portion not fulfilled will not automatically roll over; investors must submit their request for the next redemption date. For more information, please refer to the PDS.
The Underlying Fund only offers quarterly liquidity, capped at 5% of NAV. This structural limitation may restrict the amount available for redemption during periods of high withdrawal demand.
Does the Fund impose early redemption penalties?
There are no early redemption penalties for investors.
How will the Underlying Fund’s holdings be allocated?
The Underlying Fund will be allocated a certain percentage of each deal based on OHA’s Allocation Policy. The Underlying Fund’s ability to participate in any investment opportunity will depend on the allocation to OHA, as well as the allocation across OHA’s clients at the time of the opportunity, pursuant to OHA’s Allocation Policy.
Who is the Responsible Entity?
Channel Investment Management Limited
Who is the Underlying Fund Investment Adviser?
OHA Private Credit Advisors II, L. P.
Who is the Fund Distributor?
T. Rowe Price Australia
How is the Underlying Fund positioned from an asset allocation / top-down perspective?
The Underlying Fund's focus on multi-strategy credit provides access to an income-focused alternative credit strategy. The Underlying Fund has flexibility to invest up and down the capital structure across private and public markets. The Underlying Fund seeks to employ a tactical, opportunistic and nimble strategy to navigate all stages of the market cycle. Rather than building a portfolio of many strategies and/or managers to obtain the desired credit allocations, The Underlying Fund is meant to be a single point of entry into a portfolio of credit investments that will seek to take advantage of opportunities across a broad range of credit assets.
What alternative credit strategies does the Underlying Fund invest in?
- Junior Capital Solutions - focused on junior parts of the capital structure, primarily second lien loans, subordinated debt and preferred equity
- Direct Lending - primarily focused on directly originated and customised private financing solutions, focused on "large cap" senior secured direct lending, including first lien senior secured loans and unitranche loans
- Real Asset Lending - focused on providing directly originated and privately negotiated capital solutions for real assets primarily within the infrastructure, shipping, aviation and telecommunication categories
- CLOs/Structured credit - primarily collateralised loan obligations ("CLOs"), including the debt and equity tranches of CLOs that are backed by senior secured corporate loans made to companies operating primarily in the U.S. or Europe, sourced from the secondary market
- Special Situations - focused on companies experiencing financial or operational challenges, providing liquidity solutions, bridge capital and through secondary trading
- Liquid Credit - idiosyncratic credit selection within high yield bonds and leveraged loans
1 OFLEX AUD seeks to provide the same type of private credit investment solution to individual investors that were previously largely only available to OHA’s institutional clients. Institutional clients may invest in products on substantially different terms and conditions than those offered by OFLEX AUD.
2 Assets under management (AUM) estimated as of 30 June 2026. Refers to the discretionary and non-discretionary assets of investment advisory clients and of certain tactical relationships to which OHA provides management, advisory or sourcing and administrative services. AUM includes net asset value, drawn and undrawn debt at the portfolio level, portfolio value and/or unfunded capital, as applicable. AUM uses USD exchange rates as of the applicable month-end for any non-USD-denominated assets. For the CLOs OHA manages, OHA's AUM is equal to the initial principal of collateral adjusted for paydowns. Additional information on the AUM calculation methodology is available upon request. Private Strategies, Liquid Strategies and Structured Credit are based on the primary strategy of each investment vehicle and/or account, each of which may invest in multiple asset classes. The AUM provided here is distinct from regulatory assets under management (as reported on the Form ADV), GIPS assets under management calculations, and capital under management. Totals may not add due to rounding.
All information is as of 30 June 2026 unless otherwise specified.
Important Information
Channel Investment Management Limited ACN 163 234 240 AFSL 439007 (‘CIML’), is the responsible entity and manager of the T. Rowe Price OHA Flexible Credit Income Fund AUD ARSN 690 410 176 (OFLEX AUD). T. Rowe Price Australia Limited ABN 13 620 668 895, AFSL 503741 (TRPAU) acts as the distributor of OFLEX AUD. Neither CIML, TRPAU their officers, or employees make any representations or warranties, express or implied as to the accuracy, reliability or completeness of the information contained in this material and nothing contained in this material is or shall be relied upon as a promise or representation, whether as to the past or the future. This information is given in summary form, does not purport to be complete, and does not take into account the investment objectives, financial situation or needs of any person. Past performance is not a reliable indicator of future performance and returns are not guaranteed. You should obtain a copy of the Product Disclosure Statement and Target Market Determination, which is available at www.troweprice.com.au/OFLEX, before making a decision about whether to invest in OFLEX AUD.
5342852