

PRICE POINT - IN BRIEF
Global Markets: What China’s Economic Transition Means for Global Markets
November 2015
Executive Summary
This summer’s dramatic plunge in China’s stock market and the unexpected devaluation of its currency quickly reverberated around the globe—triggering market volatility, dimming growth prospects for certain industries and countries, and exacerbating pressure on emerging markets. The events also called into question the Chinese government’s ability to manage an ongoing transition from an economy led by investments and exports to one more driven by domestic services and consumption. While T. Rowe Price managers expect investors to remain jittery as this transition proceeds over the next few years, they believe that opportunities remain in companies able to flourish even in a less rapidly expanding economy, such as well-managed Chinese consumer growth firms.
IF CHINA SNEEZES, CAN THE REST OF THE WORLD AVOID CATCHING A COLD?
This summer’s dramatic plunge in China’s stock market and the unexpected devaluation of its currency quickly reverberated around the globe—triggering market volatility, dimming growth prospects for certain industries and countries, and exacerbating pressure on emerging markets.
Steep declines in Chinese markets are not new, of course. But past sell-offs have
not roiled global markets as much. The Chinese economic boom over the past
decade has made its economy the world’s second largest, accounting for a third of global gross domestic product (GDP) growth over the past three years, according to the International Monetary Fund. As a result, China has become the world’s largest market for autos and cell phones, the second-largest oil importer, and the most voracious consumer of many other commodities, particularly iron, steel, and copper—all now adversely impacted by the slowdown. Moreover, slower Chinese growth reduces growth prospects in other emerging markets, creating even more drag on global demand.
China can’t be seen
in a vacuum. It’s indicative of a
broader trend…
China’s currency devaluation in mid-August stirred fears that its economy may be slowing even more than the official reported rate of 7% so far this year, compared with a double-digit growth rate just a few years ago. A fall in Chinese manufacturing activity last summer to a three-year low added to the growing concerns.
Chris Kushlis, a T. Rowe Price fixed income sovereign analyst for Asia, expects declining Chinese growth to continue or even accelerate, with the GDP growth rate potentially falling below 4% in a few years. The devaluation, along with the government’s unsuccessful intervention in its plunging stock market, also undermined confidence in China’s leadership and, most important, in its ability to manage the transition of its economy from one led by investment and exports to one more driven by domestic services and consumption. “One of the key tenets of investors’ favorable views on China has been the belief that the government could manage this economic transition,” says Chuck Knudsen, an emerging market portfolio specialist. “Now our confidence is shaken."
U.S. EXPOSURE
Although the U.S. market suffered its first correction (a fall of at least 10%) since 2011 amid China’s tumult, it has less direct exposure to China than many other developed, and certainly emerging, countries. Exports account for just 8.9% of U.S. GDP, and exports to China are about 7.7% of all U.S. exports. So China’s exports account for only 0.7% of total U.S. GDP (compared with 2.5% for Germany, 2.7% for Japan, and 10.2% for South Korea).[1] However, Alan Levenson, the firm’s chief economist, says that China’s economic slowdown has contributed to falling energy and industrial commodity prices and slowing growth in the rest of the emerging world, which accounts for about half of U.S. exports.
“If this were just China weakening but the rest of the world reasonably healthy, we might not be seeing the U.S. stock market plunging the way it did,” Mr. Levenson says. “But we’re not talking about an environment with otherwise healthy economies. China can’t be seen in a vacuum. It’s indicative of a broader trend, particularly among emerging economies that became overextended and now have to deleverage and reduce capacity.”
Rob Sharps, a growth stock manager of institutional portfolios, agrees that China alone was not the principal cause of the sudden setback in U.S. markets. “The collapse of the Shanghai stock market brought to the fore other issues that had been simmering,” he says. “Some big emerging markets are in recession, overall global growth is slowing, S&P 500 operating profit growth this year will probably be zero, the stronger dollar makes U.S. goods more expensive overseas, the U.S. market had not had a correction in four years, and the Federal Reserve likely will be raising interest rates. So China may have been the catalyst, but you put it all together, and it’s not surprising we have run into turbulence.”
In terms of earnings, companies in the S&P 500 Index derive about one-third of their revenue from overseas operations, based on FactSet data. But China only accounted for 4.5% of their total revenue last year and 4.3% in 2013. However, some industries are significantly more affected than others—particularly industrial, machinery, and commodity producers that were big beneficiaries of the Chinese infrastructure boom.
Peter Bates, manager of the Global Industrials Fund, says China has accounted for a disproportionate share of the organic growth of the average developed market industrial company over the last several years. “So about 10% to 15% of the average industrial company’s sales come from China,” he says. “When China was growing a 10%, that would make it one-third of their organic growth. That’s effectively gone—the Chinese industrial economy is not really growing.”
So far, however, the growing Chinese consumer sector is holding up, with some consumer-oriented U.S. companies reporting strong China sales this year. But the Chinese stock market fall dimmed luxury goods makers’ prospects, a corruption crackdown has hit U.S. gaming companies in Macau, and auto sales have plummeted. T. Rowe Price managers are concerned that the consumer sector in China eventually could suffer from the loss of jobs in the industrial economy.
We believe most Asian economies should be able to successfully weather rising rates, especially if the Fed proceeds slowly…
EMERGING MARKETS
Emerging markets, dependent on Chinese demand, are now bearing the brunt of China’s travails. With the collapse in commodity prices, energy, metals, and other commodity producers in Russia, Brazil, Chile, and South Africa have been hit hard, as well as such big exporters to China as Singapore and South Korea. “China has been past its peak metals consumption for a few years, and its slowdown has had a dramatically negative effect on most metals prices,” says Rick de los Reyes, a metals and mining sector manager. “It massively developed steel production and has been exporting excess steel to the rest of world, dragging down prices.” Until recently, China accounted for 70% of the demand for seaborne iron ore, but now its steel producers are cutting costs, hitting hard the global supply chain for iron and coal.
Mr. Knudsen says other exports among emerging markets also could be affected. “While global trade has been falling, the one bright spot was China,” he says. “Now investors have been forced to rethink global growth. You have this self-feeding loop where fears of China’s slowdown have intensified, which affects growth prospects for other emerging markets and those who export to those markets.”
Debt levels have risen sharply across Asia, but debt is largely domestically owned and denominated in local currencies. Inflation is low, and most of the region runs current account surpluses. Currencies are at multiyear lows, but that helps support exports. Meanwhile, capital flight from China and other emerging markets has accelerated, with the Federal Reserve moving toward rate normalization. “In the past, emerging markets have been able to do relatively well when the Fed was gradually raising rates,” Mr. Knudsen says. “But with all the crosscurrents going on now, the prospects of the Fed raising rates—even a quarter of a percentage point—adds another layer of uncertainty. That said, we believe most Asian economies should be able to successfully weather rising rates, especially if the Fed proceeds slowly as expected.”
OUTLOOK
Mr. Knudsen says that the firm’s global emerging market strategy has not made any major adjustments as a result of the China fallout, noting that one-third of its Chinese holdings are in Internet stocks. “The secular outlook for these companies is very attractive whether China’s economy is growing at 7% or 5%,” he says. “We also have investments in well-managed Chinese consumer growth companies with high returns on equity and very attractive valuations and in some insurance companies that are benefiting from the shift in savings from property.”
New Asia Fund Manager Anh Lu says, “The China sell-off has given us the opportunity to buy other stocks in the region at much better valuations. I am optimistic that earnings for our consumer staples companies will improve
in 2016.” Generally, T. Rowe Price managers expect China’s economy to continue to downshift to a slower, higher-quality, and more sustainable level of growth. In the near term, they also anticipate more capital outflows from China and a gradual depreciation in its currency in the coming months.
This likely will put further downward pressure on regional currencies. But Mr. Kushlis says, “I don’t think there will be a major financial crisis in China any time soon, although China has experienced a runup in domestic leverage, and that has historically been correlated with financial problems and economic slowdowns in many countries. Because of the nature of China’s economic transition, it’s hard to predict how much the economy will slow.
Until the new normal in Chinese growth becomes clearer over the next few years, investors will be jittery. “We’ve long believed that China’s transition from a state-controlled to a more market-driven financial system would be a learning process,” Mr. Kushlis observes. “We should not be surprised to see pauses in this process or even periods in which the government reverts to prior policies to manage its financial system and the economy.”
China’s Real GDP Growth Rate* Has Fallen
Year-Over-Year Growth in Gross Domestic Product
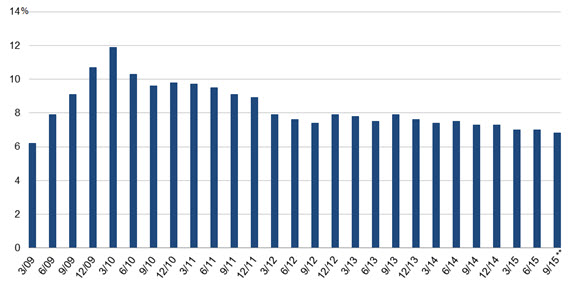
* The real GDP growth rate is the GDP growth rate adjusted for inflation.
** Estimated.
Source: Strategas Research Partners.
1 Sources: National governments, Haver Analytics, and T. Rowe Price calculations.
2015-GL-2763
IMPORTANT INFORMATION
This material is being furnished for general informational and/or marketing purposes only. The material does not constitute or undertake to give advice of any nature, including fiduciary investment advice, nor is it intended to serve as the primary basis for an investment decision. Prospective investors are recommended to seek independent legal, financial and tax advice before making any investment decision. T. Rowe Price group of companies including T. Rowe Price Associates, Inc. and/or its affiliates receive revenue from T. Rowe Price investment products and services. Past performance is not a reliable indicator of future performance. The value of an investment and any income from it can go down as well as up. Investors may get back less than the amount invested.
The material does not constitute a distribution, an offer, an invitation, a personal or general recommendation or solicitation to sell or buy any securities in any jurisdiction or to conduct any particular investment activity. The material has not been reviewed by any regulatory authority in any jurisdiction.
Information and opinions presented have been obtained or derived from sources believed to be reliable and current; however, we cannot guarantee the sources' accuracy or completeness. There is no guarantee that any forecasts made will come to pass. The views contained herein are as of the date noted on the material and are subject to change without notice; these views may differ from those of other T. Rowe Price group companies and/or associates. Under no circumstances should the material, in whole or in part, be copied or redistributed without consent from T. Rowe Price.
The material is not intended for use by persons in jurisdictions which prohibit or restrict the distribution of the material and in certain countries the material is provided upon specific request.
It is not intended for distribution retail investors in any jurisdiction.
WARNING : REFERRED CONTENT IS DEACTIVATED. TILE MAY NOT APPEAR ON LIVE SITE.
PRICE POINT - IN BRIEF
We Do Not Believe That China is Facing a Major Financial Crisis Now or Poses a Risk of Systemic Breakdown.
Read More...
WARNING : REFERRED CONTENT IS DEACTIVATED. TILE MAY NOT APPEAR ON LIVE SITE.
PRICE POINT - IN BRIEF