

Europe: The Bull-Bear Fight Rumbles On
A bull and bear fight that is getting very feisty, US inflation rising to a three year high in 2017, Europe’s market cap falling to a 25 year low, global profits potentially ticking up ending a two year recession and Value outperforming Growth for the first time in eight years. There is a lot to talk about in markets today and I haven’t even mentioned the word ‘Trump’!
To ensure we maintain a focus away from events in the US that are righty attracting so much interest, here’s a succinct case against and then for European equities as investors ponder their asset allocation into 2017.
THE CASE AGAINST EUROPEAN EQUITIES
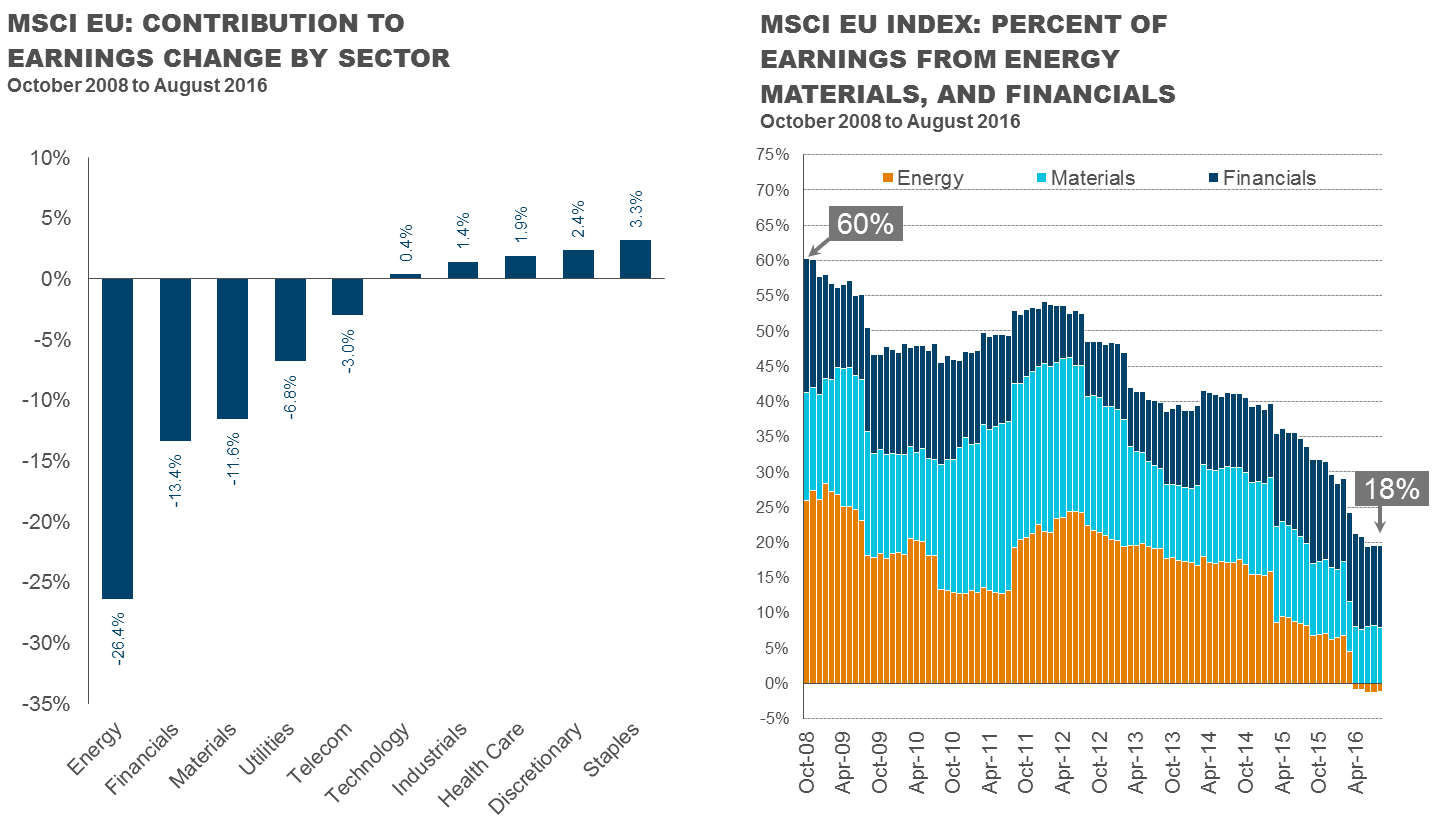
Europe’s profitability has changed dramatically due to structural reasons – oil, materials and financials have seen profits collapse, some of which is permanent and should impact investors’ perception of future earnings power/growth and be priced into valuations.
Figure 1: European Profits – Why So Bad?
Past performance is not a reliable indicator of future performance.
Chart is shown for illustrative purposes only and does not represent the performance of any specific security.
Sources: FactSet, MSCI
THE CASE FOR EUROPEAN EQUITIES
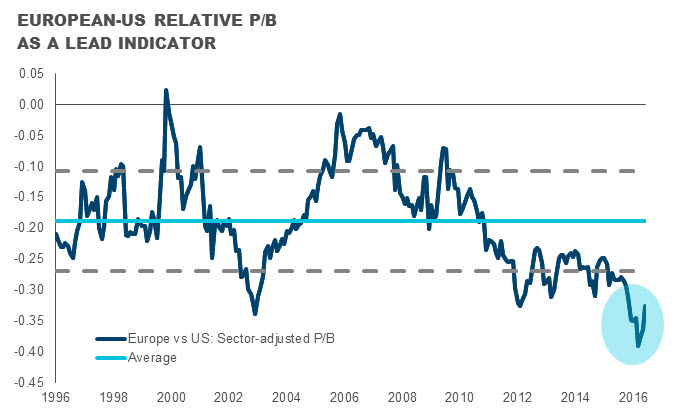
But when you look at European valuations versus the US, levels have clearly reached an extreme point and this measure has turned during the summer. If you’re a cyclical believer (a prolonged turn usually coincides with global economic growth accelerating – think late 90’s, mid 2000’s) or a mean-reversionist (given valuations look so cheap on a relative basis), Europe no doubt offers real opportunity today. Given the challenges ahead, however, the need to stay selective is as important as ever.
Figure 2: Europe – Inflection or Relief?
Past performance is not a reliable indicator of future performance.
Source: FactSet
GCC83165
重要資訊
本文件(包括其中所載的任何陳述、資訊、數據和內容)以及與本文件一併提供的任何資料、資訊、圖像、連結、聲音、圖像或視頻(統稱為「資料」)乃由普信提供,並僅作一般資訊用途。本資料並不擬供在禁止或限制分發本資料的司法管轄區和在本資料須按特定要求提供的若干國家之人士使用。本資料不擬派發予任何司法管轄區的散戶投資者。在任何情況下,本資料的全部或部分內容均不得在未經普信同意下複製或再分發或出示予任何人士。本資料並不構成於任何司法管轄區分銷、要約、邀請、建議或徵求發售或購買任何證券。本資料並未經由任何司法管轄區的任何監管機關審閱。本資料並不構成任何投資意見,不得加以依賴。投資者務請在作出任何投資決策前先尋求獨立法律和財務意見(包括有關稅務後果的意見)。
