

European High Yield - March 2016
The Rise of the Fallen Angels
The number of issuers downgraded from investment-grade into high yield is gathering pace. February marked a record month for both the number of fallen angels globally (30) and their value ($115.8 billion).[1] Given the deterioration in the global macro environment, particularly the sharp decline in commodity and oil prices seen over the past year, there is the potential for many more fallen angels in 2016. In my view, this could have profound implications for the asset class in the coming quarters and beyond, and here's why.
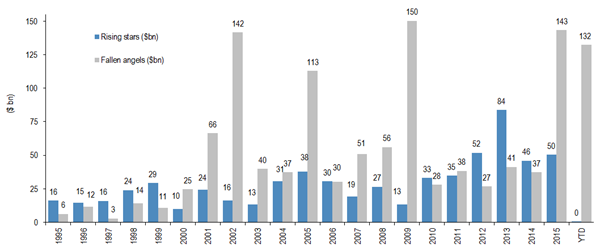
Figure 1: Rising Stars and Fallen Angels by Dollar Amount
As of February 29, 2016
Source: J.P. Morgan
First, the composition of high yield benchmarks will change. At the end of February, approximately $132.2 billion of debt globally had been downgraded into junk since the start of the year, according to J.P. Morgan. That compares with $143.1 billion for the whole of 2014 and a record $150.2 billion in 2009 (see Figure 1). The sheer amount we have seen in just two months is unprecedented and it is already impacting the benchmarks. Take the recent downgrade to high yield of Anglo American; the mining giant now makes up 2.1% of the main European high yield bond market, with 10 bonds spanning six years of maturities. This is just one example; there are likely to be more.
For us as investors, the potential opportunity set will widen. To properly evaluate these companies transitioning into high yield, we believe close collaboration with our investment grade analysts and equity colleagues is the best approach. This provides us with the best opportunity to ensure a seamless coverage of fallen angels and crossover credits. The ability to leverage this expertise gives us an information advantage, which will be critical with more companies expected to lose their investment-grade ratings this year.
Fallen angels have the potential to change the size, depth and composition of high yield. Our focus remains on bottom-up credit research, but collaboration with investment grade analysts and equity colleagues will also be vitally important to enable us to steer through this next stage of growth in the asset class.
The views contained herein are as of 29 February 2016 and may have changed since that time. Unless indicated otherwise the source of all market data is BofA Merrill Lynch. All data shown in US dollars.
2016-GL-3596
重要資訊
本文件(包括其中所載的任何陳述、資訊、數據和內容)以及與本文件一併提供的任何資料、資訊、圖像、連結、聲音、圖像或視頻(統稱為「資料」)乃由普信提供,並僅作一般資訊用途。本資料並不擬供在禁止或限制分發本資料的司法管轄區和在本資料須按特定要求提供的若干國家之人士使用。本資料不擬派發予任何司法管轄區的散戶投資者。在任何情況下,本資料的全部或部分內容均不得在未經普信同意下複製或再分發或出示予任何人士。本資料並不構成於任何司法管轄區分銷、要約、邀請、建議或徵求發售或購買任何證券。本資料並未經由任何司法管轄區的任何監管機關審閱。本資料並不構成任何投資意見,不得加以依賴。投資者務請在作出任何投資決策前先尋求獨立法律和財務意見(包括有關稅務後果的意見)。


