

PRICE PERSPECTIVE - IN DEPTH
Global Fixed Income: A Case for Looking Further Afield
March 2015
EXECUTIVE SUMMARY
- Weak growth, falling inflation, and unorthodox central bank policy have culminated in an unprecedented low interest rate environment across much of Europe. With bond yields scant and interest rate risk high, diversifying fixed income allocations globally can boost return potential and possibly provide some protection when rates eventually rise.
- The growth and maturation of emerging bond markets has opened new doors to invest in companies and countries offering superior yields but with less leverage than developed market peers.
- High-grade and high yield credit markets have grown increasingly diverse geographically, allowing investors to take advantage of mispriced securities in less efficient markets and regional valuation and performance disparities.
- Increasingly unsynchronized central bank policy is likely to fuel higher volatility in rates, while also creating duration and curve opportunities in sovereign bond markets. Active currency pairings are another means of exploiting the theme of divergent growth and monetary policy trends.
- Institutional investors have various strategy options to gain exposure to the global fixed income opportunity set, depending on their individual objectives and risk tolerances.
Investors value high-quality government bonds for their liquidity and perceived risk-free return. But with negative yields on offer in several European countries, many investors are questioning whether they should pay for the privilege of lending governments money while risking capital losses should rates rise. Amid highly unorthodox central bank policy, deflation concerns, and tepid growth, two-year sovereign notes recently yielded less than 0% in France and Finland. Five-year maturities proffered negative yields in Germany, Denmark, and the Netherlands. In Switzerland, investors must look beyond 10 years to find positive yields.
Tumbling sovereign yields have driven investors into riskier assets in search of higher returns. Increased investor demand and falling underlying rates have distorted valuations in European credit markets. In late February, euro corporate bond yields fell to a record low 0.83%.1 The extremely low yields on sovereign debt are likely to continue to fuel strong demand for high-grade corporates, but potential for additional capital appreciation is limited. And with yields at these extremely low levels, duration risk is more pronounced.
But an environment of ultralow rates and heightened risks also presents an opportunity for institutional investors to expand their horizons beyond home country or regional borders. Higher yields can be obtained in sovereign and credit markets with stronger growth tailwinds, and increasing global exposures can provide diversification benefits. Investing globally may offer some protection when developed market rates eventually begin to rise. And a global approach provides additional alpha levers for portfolio managers to pull, including tactical sector and country allocations, targeted duration and curve management, and active currency exposures.
A larger opportunity set makes it more feasible for institutional investors to diversify fixed income allocations globally, as many have already done with their equity allocations.
A BROADENING FIXED INCOME OPPORTUNITY SET
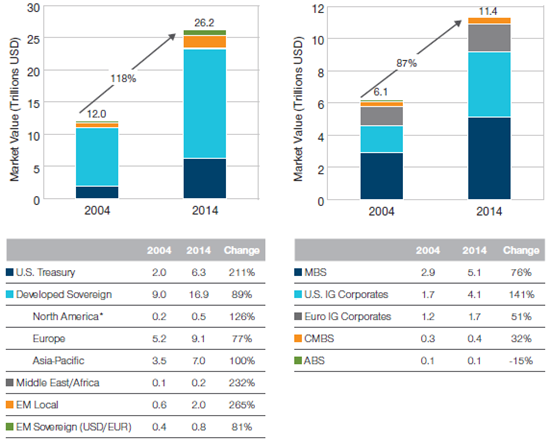
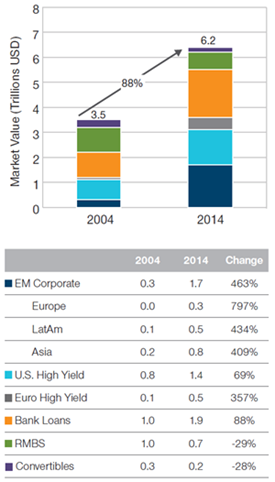
The investable fixed income universe has greatly expanded over the past 10 years (see Figure 1). It now encompasses a wider array of rate and credit instruments, ranging from high-quality government bonds to higher-beta spread product. This enables the construction of return-seeking or defensive portfolios (or a combination thereof) depending on investors’ investment objectives and risk tolerances.
A larger opportunity set makes it more feasible for institutional investors to diversify fixed income allocations globally, as many have already done with their equity allocations. A 2014 survey by Mercer found that, on average, European pension plans allocated more of their portfolio holdings to nondomestic equities than to domestic equities (21% versus 13%, respectively). In contrast, fixed income allocations had a distinctly local bias: While 42% of portfolios were allocated to various types of domestic bonds, only 4% were allocated to foreign government and corporate bonds combined.2
Figure 1: Broad growth in the global opportunity set
Global Sovereign Global Investment Grade
Global Opportunistic
Sources: Bank for International Settlements, Bank of America/Merrill Lynch, Barclays, CoreLogic, JP Morgan, S&P/LSTA, Haver Analytics, and T. Rowe Price.
*Canada and Latin America.
A WEALTH OF OPPORTUNITIES IN RAPIDLY GROWING EMERGING MARKETS
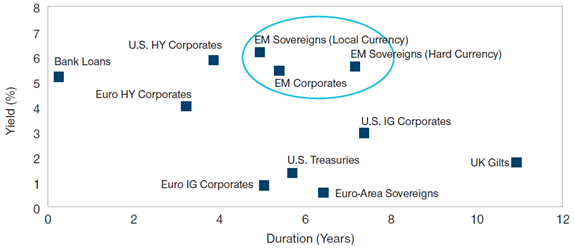
Emerging markets (EM) is an area of global fixed income in which investors appear to be particularly underinvested. Developing countries account for nearly 40% of global gross domestic product (GDP).3 Yet, according to Mercer, less than one-fifth of surveyed pension plans held dedicated EM bond allocations. Challenging liquidity and concerns about volatility likely deter some investors. But relatively attractive yields help compensate for the risks (see Figure 2).
Figure 2: Variation in yields around the globe
As of February 27, 2015
Sources: Bank of America/Merrill Lynch, Barclays, JP Morgan, S&P/LSTA, and T. Rowe Price.
Although still small in comparison with more traditional sovereign and investment-grade credit sectors, EM issuance has proliferated over the past 10 years, particularly in the corporate and local currency sectors. This expansion provides investors with more opportunities to earn higher coupons, as well as potential capital appreciation from spread compression from countries and companies supported by stronger growth tailwinds and lower debt burdens than the typical developed market.
EM credit quality has improved dramatically over the past two decades, making it more palatable for institutional investors. “If you look back to the early 1990s, only 2% of the countries that we can invest in were rated investment grade. Today, it’s about 73%,” says Samy Muaddi, a portfolio manager/analyst specializing in EM corporate debt. “There certainly are outliers—the Argentinas and Venezuelas of the world—but this is a much different asset class than it used to be. Many of these countries have actually emerged, if you will.”
The maturation of the asset class has opened new investment doors. Taking advantage of improved credit quality and strong government balance sheets, developing countries are now issuing more debt in their own currencies than in “hard” currencies like the dollar and euro. Although much larger in total size, the local market is narrower in scope than the traditional external sovereign market, with fewer countries represented. But it offers higher yields, better liquidity, and less credit risk. Currency volatility is a major risk factor, as the risk of exchange rate fluctuations is transferred from the issuer to foreign creditors. Yet unhedged FX exposures can be a valuable source of alpha—particularly when developed market central banks are intent on weakening their home currencies.
The emerging corporate sector has likewise grown at a rapid clip. From less than 30 issuers a decade ago, the opportunity set has blossomed to over 550 names from 49 countries,4 many of them industry leaders. Notably, the rapid growth has not been accompanied by an increase in leverage; companies have mainly tapped the capital markets to refinance bank loans over a longer term at attractive rates.
“There’s less overall leverage in emerging markets, both at the sovereign level—reflected in debt to GDP—and at the corporate level,” says Muaddi. “The combination of more yield and less leverage is something we find very compelling. Like the equity investor’s price-to-earnings ratio, we look at the yield-to-leverage ratio in fixed income.”
GLOBALIZATION OF CREDIT MARKETS ALLOWS FOR GREATER DIVERSIFICATION
The world’s credit markets have become increasingly complex and interwoven as they have grown. Indeed, with the development of the EM corporate sector, the demarcations between investment-grade and high yield credit have blurred. EM corporates offer yields on par with U.S. below investment-grade corporates even though a majority of issuers have earned investment-grade ratings. As such, some names may merit consideration in both investment-grade and high yield portfolios.
The U.S. and Europe still dominate global investment-grade credit benchmarks, as companies have taken advantage of historically low rates to issue large quantities of new bonds. However, there is a diverse and growing set of high-quality issuers from outside these traditional markets. For instance, Asian credit markets are flourishing, benefiting from investors’ pursuit of higher yields and an ongoing trend of bank disintermediation.
With economies around the globe on varying growth paths, credit cycles have likewise become less synchronized. According to Steve Boothe, an associate portfolio manager for T. Rowe Price’s investment-grade corporate team, this can create opportunities to identify mispriced securities in less efficient markets. By looking globally, investors can also benefit from cross-currency relative value analysis; for example, purchasing a European bank name that has issued in the U.S. can maximize yield in the current environment. “Although we like European credits, we’re finding better carry in the U.S. dollar and British pound markets than in the euro market,” Boothe notes.
In 2008, every central bank in the world was cutting rates, so there was a huge amount of synchronization. Now we are in a world of desynchronization and divergence,” says Arif Husain, T. Rowe Price’s head of international fixed income.
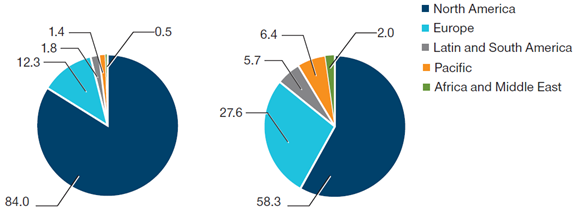
The high yield asset class has undergone a major evolution, allowing investors to cast a much wider net across both countries and sectors. Overwhelmingly U.S.-based a decade ago, today nearly half of global high yield benchmarks consist of issues from outside North America (see Figure 3). There are also more types of credit instruments to choose from. For example, there has been considerable growth in leveraged loan markets, providing opportunities to invest higher in companies’ capital structures and potentially gain some protection against rising rates via their floating rate features.
Figure 3: A more geographically diverse high yield universe
Sources: Bank of America/Merrill Lynch and T. Rowe Price.
Diversifying globally can reward investors when different regional cycles produce dispersion in performance. As a case in point, the European high yield market outperformed the U.S. high yield and EM corporate debt markets over the past three years despite the eurozone’s economic woes.5 “This is a great example of how macro, top-down fixed income managers often get it wrong,” says Mark Vaselkiv, head of T. Rowe Price’s global high yield bond team. “Much of the news from Europe has been negative. Yet there are still world-class companies in very stable industries.”
Following this stretch of outperformance, European high yield valuations look less compelling at the broad sector level. The U.S. high yield market endured turbulence in late 2014 due to its much heavier commodity exposure, resulting in more attractive valuations. The oil price shock also pressured EM credit spreads wider even though many issuers in importing countries may actually benefit from lower commodity prices. While there are still many interesting first-time issuers and improving credit stories in Europe, and the European Central Bank’s (ECB) actions will be supportive of risk appetite, investors can benefit from scouring the full global opportunity set for the best ideas.
Investing globally presents opportunities to profit from dislocations driven by economic and geopolitical uncertainty. “Russia was the epicenter of volatility last year. But sometimes you have to run toward the fire and look for opportunities because there are solid companies even in places like Russia,” says Vaselkiv. He adds: “Successful investors in high yield are those who take a long-term approach and can accept volatility. Investors ultimately benefit over the long term from the power of compound interest and managers who take advantage of dislocations—like when oil prices fall by more than half. At those points of the cycle, we can find securities trading at significant discounts and add a component of capital appreciation as well as high current income.”
DIVERGENT CENTRAL BANK POLICY CREATES OPPORTUNITIES IN RATES
The sharp decline in the prices of oil and other commodities since mid-2014 has reduced inflation pressures in some energy-importing countries while hurting economic growth prospects for major commodity exporters. As a result, a number of countries, including Canada, Australia, India, and Indonesia, have recently joined the ECB in loosening monetary policy.
But other countries are biased toward tightening. Although concerns about global risks and below-target inflation could delay its plans, the Federal Reserve may begin raising short-term rates as early as June with slack in the U.S. labor market continuing to ebb. And Brazil’s central bank, after pausing during a presidential election cycle, has resumed raising rates to rein in elevated inflation. The global variance in monetary policy will likely lead to higher volatility in rates, but it also creates opportunities in heterogeneous sovereign bond markets.
“In 2008, every central bank in the world was cutting rates, so there was a huge amount of synchronization. Now we are in a world of desynchronization and divergence,” says Arif Husain, T. Rowe Price’s head of international fixed income. For example: “A few hours after the Fed announced the end of its asset purchases, the Bank of Japan decided to flood the market with a huge easing program. Think about the monetary experiment the Europeans are about to embark on. In emerging markets, some countries are raising rates while some are cutting.”
Anticipation of the ECB’s asset purchase program helped drive valuations on eurozone sovereigns to extremely rich levels before it even commenced. As its bond purchases begin, spreads could tighten further in higher-yielding peripheral markets like Portugal. However, downside risks exceed upside risks with yields at these extremely low levels. A weaker euro, less austere fiscal policy, and thawing credit conditions suggest stronger eurozone growth in the second half of 2015. This should eventually drive European yields higher, cutting into bond prices.
Rising rates in the U.S. could also apply upward pressure on global yields, as occurred during 2013 when Fed officials began discussing tapering asset purchases. However, domestic economic conditions and policy responses remain the primary driver of local rates. In a divergent rate environment, focusing duration exposures on countries that are entering easing cycles or where yields are already high is a prudent strategy. “While the Fed’s raising rates is not going to be great for bonds,” says Husain, “a lot of countries are going to be cutting rates. That provides a great opportunity.”
CENTRAL BANKS ALSO DRIVING CURRENCY VALUATIONS
Along with duration management, currency exposures are another means of exploiting the theme of diverging central bank policy. A number of factors drive currency movements, including foreign demand for investment assets and changes in current account balances. The level of short-term rates is also important, as higher rates make holding currencies more attractive. As an additional source of alpha, managers can pair long and short foreign exchange positions based on disparate economic and policy expectations, taking into account what has already been priced into currency markets.
Central bank actions have whipsawed currency valuations over the past year. The U.S. Fed’s bias toward tightening while many other central banks are loosening policy contributed to overwhelming dollar strength versus most currencies. Meanwhile, the euro tumbled in value—not only versus developed market currencies like the dollar and pound, but also relative to many EM currencies—as the ECB made holding euros unattractive. The stronger dollar / weaker euro trend may persist in the near term, but the pace will likely slow.
Over the longer term, currencies from countries enacting economic reforms, such as Mexico and India, should do well versus currencies from slower-growing markets. This creates opportunities to make controlled relative value trades based on growth disparities. Steve Huber, manager of the Global Multi-Sector Bond Strategy, has favored the Polish zloty over the euro within European currencies. “Poland has better growth prospects than the eurozone, and the euro still looks to be on a downtrend,” he says. He notes that because the two currencies are situated close geographically, pairing the zloty with the euro mutes some of the volatility that may result from pairing the zloty with the dollar.
MULTIPLE WAYS TO ACCESS GLOBAL FIXED INCOME
Institutional investors have various options for diversifying globally. A more traditional route is a core allocation benchmarked to an index of high-quality government and corporate bonds, such as the Barclays Global Aggregate. This provides exposure to the world’s major debt markets, along with modest exposure to the larger EM countries. Downsides in the current environment are very low yields accompanied by lengthening durations. And there is a risk that safe-haven sovereigns will be less effective as a hedge against equity volatility than they have been in the past, as yields can only fall so far.To increase portfolio yield, investors frequently supplement traditional sovereign and credit holdings with allocations to a few return-seeking sectors such as EM bonds and/or below investment-grade credit. This can boost returns without significantly increasing portfolio volatility. A disadvantage of these standalone allocations is that portfolios may still be overly concentrated. And they may lack the flexibility to fully take advantage of rapidly changing market conditions and turns in credit cycles.
A more dynamic, diversified alternative to generate higher income is to supplement core holdings with a global multi-sector allocation. Working within client guidelines, a manager strategically allocates across a range of sectors and can quickly make tactical adjustments when valuations become compelling or risks rise in areas of the markets. “We believe that having wide latitude to invest across sectors is important,” says Huber. “It allows us to take risk when we’re being paid adequately to take it but also allows us to become more defensive with more liquid and higher-quality securities when the environment warrants.”
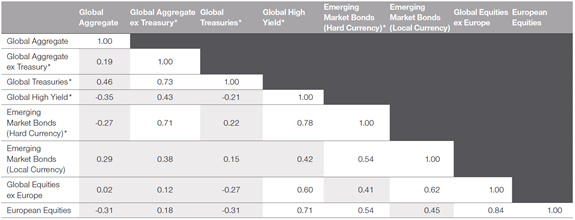
Combining a variety of sectors in a portfolio can provide valuable diversification benefits. As shown in Figure 4, some sectors in a hypothetical multi-asset portfolio have relatively high correlations with one another, but many are low or even negative. And if sector valuations are uninspiring, a manager can emphasize different alpha sources to boost returns and manage risks. “From 2009 to 2011, the opportunities were clearly in sector allocation, as credit was very cheap,” says Huber. “But since 2012, sources of expected return have been more balanced, with currency and duration management providing more opportunities given divergent global monetary policy cycles.”
Figure 4: Diversification benefits may arise from low return correlations
*Returns hedged to euros.
Correlation coefficients calculated from monthly total returns in euros from January 2004 through December 2014. Sources: Barclays, JP Morgan, MSCI, and T. Rowe Price.
Finally, investors may desire to flexibly and dynamically access the full global opportunity set, but in a more defensive manner. In an environment where income levels are low and rising rates could potentially inflict capital losses on bonds and fuel volatility in risk assets, non-traditional unconstrained bond strategies are an area of growing interest. “Clients are telling us that they need income and downside protection, but they also want traditional fixed income qualities like liquidity and diversification,” says Husain. “When equities and risk assets go down in value, clients want something in their portfolio that is stable or even goes up.”
An appeal of unconstrained strategies is their benchmark agnosticism. Rather than tracking an index that more heavily weights the largest debt issuers, they typically use a cash benchmark and seek to provide consistent, positive returns throughout the market cycle by focusing on the best ideas in rates, currencies, and credit. “We have the flexibility to invest in credit when it makes sense,” says Husain. “However, we also have the flexibility to invest in government bonds and currencies. We are taking a very global approach, which I think is very different from what some others are doing.”
1 Based on the Barclays Euro-Aggregate Bond Index’s yield to worst, which assumes the lowest possible yield for callable bonds. As of February 26, 2015.
2 Mercer, Asset Allocation Survey: European Institutional Marketplace Overview 2014.
3 Source: The International Monetary Fund’s World Economic Outlook Database, October 2014. GDP at current prices.
4 Based on the JP Morgan CEMBI Broad Diversified Index.
5 On a currency-hedged basis.
2015-GL-1583
IMPORTANT INFORMATION
This material is being furnished for general informational and/or marketing purposes only. The material does not constitute or undertake to give advice of any nature, including fiduciary investment advice, nor is it intended to serve as the primary basis for an investment decision. Prospective investors are recommended to seek independent legal, financial and tax advice before making any investment decision. T. Rowe Price group of companies including T. Rowe Price Associates, Inc. and/or its affiliates receive revenue from T. Rowe Price investment products and services. Past performance is not a reliable indicator of future performance. The value of an investment and any income from it can go down as well as up. Investors may get back less than the amount invested.
The material does not constitute a distribution, an offer, an invitation, a personal or general recommendation or solicitation to sell or buy any securities in any jurisdiction or to conduct any particular investment activity. The material has not been reviewed by any regulatory authority in any jurisdiction.
Information and opinions presented have been obtained or derived from sources believed to be reliable and current; however, we cannot guarantee the sources' accuracy or completeness. There is no guarantee that any forecasts made will come to pass. The views contained herein are as of the date noted on the material and are subject to change without notice; these views may differ from those of other T. Rowe Price group companies and/or associates. Under no circumstances should the material, in whole or in part, be copied or redistributed without consent from T. Rowe Price.
The material is not intended for use by persons in jurisdictions which prohibit or restrict the distribution of the material and in certain countries the material is provided upon specific request.
It is not intended for distribution retail investors in any jurisdiction.
MARKET COMMENTARY - EQUITY
WARNING : REFERRED CONTENT IS DEACTIVATED. TILE MAY NOT APPEAR ON LIVE SITE.
PRICE POINT - IN BRIEF
WARNING : REFERRED CONTENT IS DEACTIVATED. TILE MAY NOT APPEAR ON LIVE SITE.
PRICE PERSPECTIVE - IN DEPTH