Anthropic’s IPO and the next phase of AI
November 2026, Equity
The details
Anthropic’s initial public offering marks an important milestone in the evolution of AI, bringing one of the leading developers of frontier AI models into public equity markets. For investors, however, the significance extends beyond the listing itself. Anthropic’s financial disclosures provide an unusually detailed view of the commercialization of frontier AI, revealing rapidly expanding enterprise adoption, improving compute efficiency and the considerable investment required to sustain technological leadership.
The IPO reinforces our view that AI could become a major productivity driver. More importantly, it illustrates how the investment opportunity is shifting from building increasingly capable models toward deploying agents that perform economic work. That evolution has implications for which technology businesses ultimately capture value—and whether the returns justify the capital being committed.
What we believe it means for the AI investment cycle
1. Anthropic’s growth demonstrates the commercial potential of AI
Anthropic’s IPO follows a period of extraordinary growth. More than 11,900 customers each generated at least $100,000 in trailing 12-month revenue for Anthropic as of September 30, 2026, up from more than 950 a year earlier. According to Anthropic's IPO registration filing with the US Securities and Exchange Commission (SEC), the company’s annualized revenue run rate—the amount it would generate over a year at its current pace—reached approximately $81 billion by the end of October, up from $71 billion a month earlier.
There is considerable room for further growth. The IPO filing also showed that more than half of Fortune 500 companies generated at least $100,000 in revenue on a TTM basis for Anthropic as of September 30, 2026. Yet among its publicly traded Fortune 500 customers, spending on Anthropic's services accounts for less than 0.1% of their total expenses, on average, the filing said.
Anthropic’s unit economics have improved, though not in a straight line. Compute and infrastructure expenses fell from $2.51 per dollar of revenue in early 2025 to $0.48 in the second quarter of 2026, then rose to about $0.58 in the third quarter, when the company bought $5 billion of short-notice capacity at a premium to its multiyear contracts (Figure 1). Higher compute costs, together with a $2 billion non-cash charge1, contributed to a swing of approximately $1 billion operating income2 in the second quarter to a $567 million operating loss in the third. In our view, the swing says less about weakening economics than about how scarce reliable compute remains. Demand outran the capacity Anthropic had contracted in advance.
Anthropic’s compute expense per revenue dollar remains below 2025 levels
Compute and infrastructure expense per dollar of revenue, by quarter
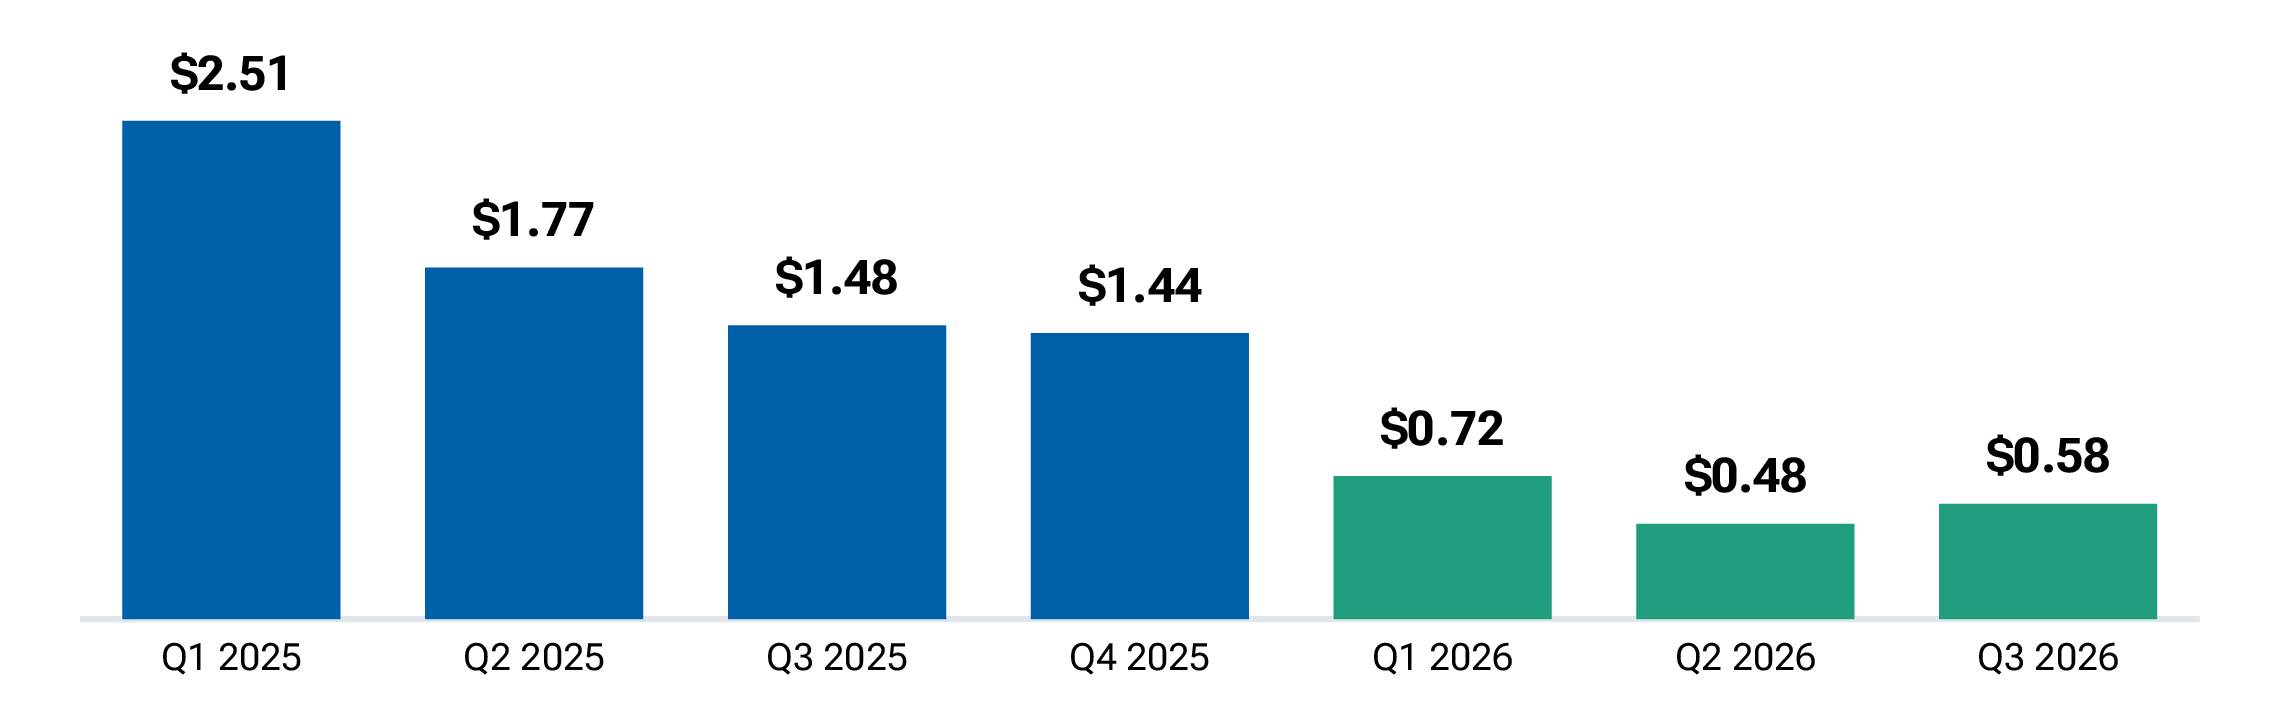
As at: 30 September 2026
Source: Anthropic. Figures in USD.
Beyond operating leverage, we believe AI could improve its own economics by accelerating model development and compute efficiency. This creates a reinforcing cycle in which increasingly capable models help reduce the cost of delivering intelligence.
These figures highlight both AI’s commercial potential and the challenges of translating rapid growth into sustainable profits. Sequential revenue growth also slowed from 144% in the second quarter to 47% in the third as the revenue base expanded. Enterprise adoption may also lag technological advances as businesses adapt their systems and workflows.
What does this mean? AI is moving beyond experimentation into measurable commercial demand, with—in our view—substantial room for further adoption. The question is whether growth and improving compute efficiency can translate into sustainable profitability. Monthly additions to Anthropic’s run-rate revenue, approximately $10 billion in October, could be an important indicator.
2. Frontier intelligence and autonomous agents could unlock the next phase of demand
Dom Rizzo, portfolio manager of our Global Technology Equity Strategy and co-portfolio manager of our Large Cap Core Growth Equity Strategy, believes much of the value in AI could accrue to leading-edge models, even if cheaper alternatives handle most routine tasks. Customers may be willing to pay a premium for models that reliably complete complex, high-value work.
Maintaining that advantage requires continuous innovation. Anthropic’s substantial research and development spending highlights the cost of staying ahead, while intense competition from OpenAI, Google and lower-cost alternatives could pressure pricing. Rizzo believes that long-term returns will depend on whether frontier AI developers can turn technological leadership into durable platform economics, differentiating their products and capturing more value despite substantial capital requirements and competitive pressures.
The next phase of growth could come from autonomous agents. Anthropic’s Claude Code and Cowork illustrate the shift from AI tools that respond to prompts toward systems capable of writing software, accessing data and completing multistep tasks. As these systems become more capable and less expensive, a wider range of work could become economically viable.
The opportunity may extend beyond selling access to increasingly capable models. Anthropic is seeking to become a broader platform for enterprise knowledge work, integrating models, applications and autonomous agents into everyday workflows. If successful, this could create a competitive advantage and stickier customer relationships than selling intelligence on a consumption basis alone.
However, widespread adoption will take time. Businesses must address security, governance and integration challenges before deploying agents at scale.
What does this mean? The next wave of AI demand could come from agents performing valuable economic work, rather than simply more people using AI tools. But technological leadership will not necessarily translate into profits. Integrating intelligence into enterprise workflows could ultimately determine which companies capture lasting economic value.
3. Anthropic’s economics reinforce the AI infrastructure opportunity
Anthropic's rapid growth appears to reinforce the investment case for AI infrastructure, while the shift toward autonomous agents could broaden demand beyond the GPUs traditionally associated with model training.
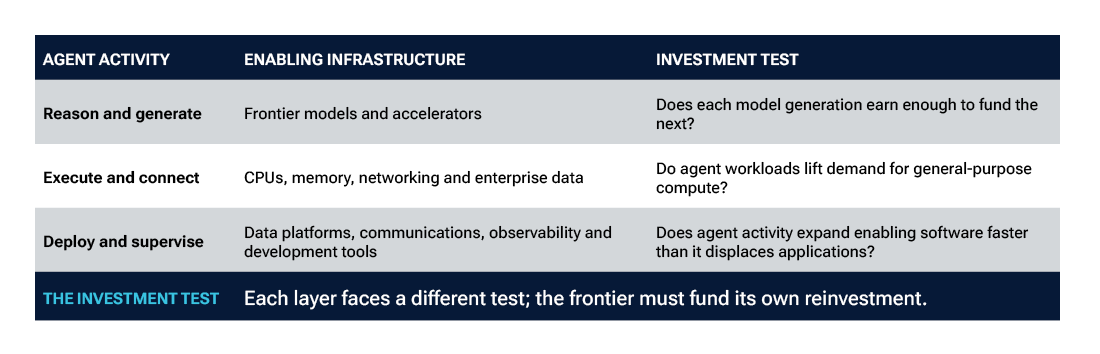
Agents that execute code, access databases and coordinate applications require supporting infrastructure, potentially increasing demand for CPUs, memory, networking, storage and other technologies. We remain particularly constructive on CPUs (Figure 2).
Where AI agents could createinvestment value
How agentic activity maps to infrastructure and the investment test
Source: T. Rowe Price
Improving AI efficiency could reinforce this demand by making more applications economically viable. Cheaper intelligence does not necessarily mean less demand for computing power; it could encourage wider adoption.
Recent weakness in semiconductor shares has sharpened an important distinction. A correction in how AI infrastructure is financed and priced is not the same as a decline in demand for AI capability. Suppliers that raised prices aggressively during shortages, that are expanding capacity, or that rely on customers sensitive to financing costs face greater risks as conditions normalize. Segments where supply remains constrained and inventories are lean appear better placed. Anthropic’s decision to pay a premium for short-term capacity in the third quarter suggests that supply constraints can persist even as conditions normalize elsewhere.
However, strong demand does not guarantee attractive returns for every supplier. Anthropic’s approximately $895 billion of purchase and lease commitments, substantially all related to compute and infrastructure, highlight the capital intensity of AI, while financing costs, capacity constraints and utilization remain important risks. Where supply shortages ease, competitive advantages may increasingly depend on execution and technological differentiation rather than scarcity alone.
What does this mean? We believe AI infrastructure demand could remain durable even as individual bottlenecks ease. We favor companies with improving fundamentals and profitable demand over those relying predominantly on scarcity, while remaining attentive to financing and capital intensity.
4. Anthropic’s IPO creates new considerations for public-market investors
Anthropic’s arrival in public equity markets could mark the beginning of a broader expansion in the number of listed companies providing exposure to frontier AI. For investors, the IPO introduces another question alongside technological leadership and commercial growth: how much future success is already reflected in valuations?
A rapidly expanding addressable market does not guarantee attractive shareholder returns. Sustaining frontier-model leadership requires substantial reinvestment, while competitive pressures and the pace of enterprise adoption could affect future profitability. Regulatory and political scrutiny adds another risk. If adoption leads to visible job displacement, political pressure could affect both operating forecasts and the multiples investors are willing to pay.
The listing also has implications for benchmark exposure. Anthropic’s eventual representation in major equity indexes will depend not simply on its valuation, but also on the proportion of shares eligible for inclusion, applicable lockup provisions (restrictions on when existing shareholders can sell their shares) and individual index methodologies.
As additional shares become eligible and indexes rebalance, passive strategies may need to adjust their exposure. Active managers, by contrast, can assess the company’s underlying economics and valuation independently of its benchmark weight.
The timing and magnitude of these changes remain uncertain. Importantly, benchmark inclusion does not establish investment merit.
What does this mean? In our view, Anthropic’s IPO expands the ways investors can gain exposure to AI, but also reinforces the importance of investment discipline. Managers must distinguish between the growth of the AI market, the businesses best positioned to capture its value and the prices paid for that exposure.
 Jennifer O'Hara Martin
Global Equity Portfolio Specialist